
The Restaurant Owner Who Couldn't Get a Mortgage Until We Looked at Her Bank Statements
Reviewed by Peter Irungu, NMLS #2751063 | Last updated October 23, 2026
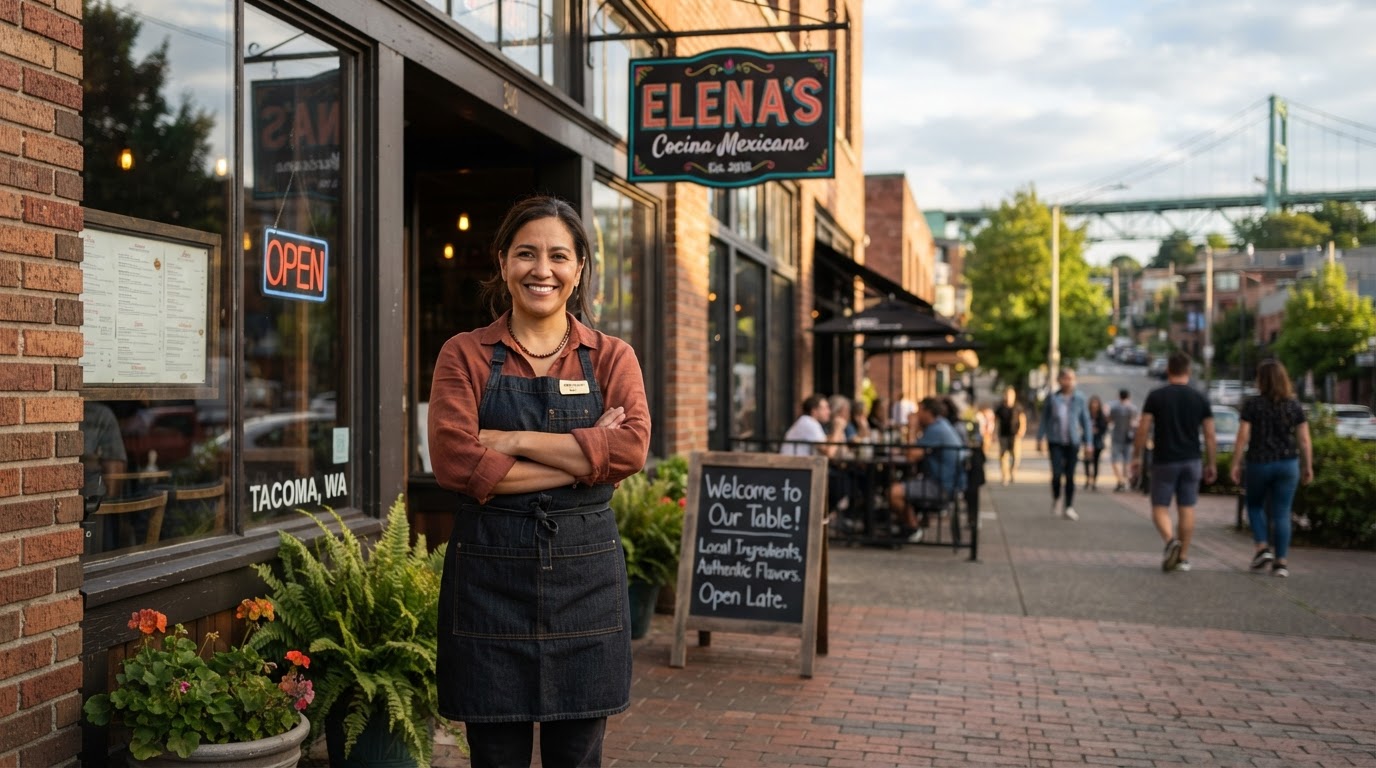
Priya opened her Tacoma restaurant in 2021. By 2026, it was thriving a 70-seat spot on Sixth Avenue with a loyal following, a second location in the works, and revenue most small business owners would envy. But when she tried to buy a home in Puyallup, three different banks told her the same thing: 'Your tax returns don't show enough income.'
Here's why that happened and how a bank statement loan got her into a three-bedroom home with a yard for her kids in 38 days.
The Tax Return Trap
Like most self-employed business owners, Priya worked with a CPA who maximized her deductions. Equipment depreciation, business meals, vehicle expenses, home office deductions all legal, all smart, and all of them reduced her adjusted gross income on paper.
The result: her tax returns showed about $52,000 in net income. Her actual cash flow the money flowing through her business and personal accounts was closer to $180,000 per year. But traditional lenders don't see cash flow. They see tax returns.
This is the single most common reason self-employed borrowers get denied. It's not that they can't afford a home. It's that the tax code and the mortgage underwriting system don't speak the same language.
How Bank Statement Loans Work
A bank statement loan looks at 12 to 24 months of your actual bank deposits instead of your tax returns. The lender calculates qualifying income from the real money flowing through your accounts not the number your CPA optimized for tax purposes.
In Priya's case, we used 24 months of business bank statements. Her average monthly deposits were about $15,000. After applying a 50% expense factor (standard for many programs), her qualifying monthly income was $7,500 or $90,000 annualized. That was more than enough to qualify for a $520,000 home.
No tax returns. No W-2s. No adjusted gross income. Just the actual cash flow her business generated.
What Priya Needed to Qualify
The requirements were straightforward: two years of self-employment history (verified through her business license and a CPA letter), 24 months of business bank statements, a credit score of 680 (Priya's was 742), and a 15% down payment.
On a $520,000 home, 15% down is $78,000. Priya had been saving aggressively and had $95,000 set aside more than enough for the down payment plus closing costs and reserves.
The trade-off: bank statement loans typically carry slightly higher rates than conventional financing. For Priya, the ability to qualify at all was worth it. She could refinance into a conventional loan later if her tax return income caught up or she could keep the loan and focus on growing her business.
The Closing and the Lesson
Priya closed on a three-bedroom home in South Hill Puyallup with a quarter-acre yard, a kitchen big enough to test recipes, and a mortgage payment she could comfortably afford. Total time from our first conversation to keys: 38 days.
The lesson she wanted me to share: 'Don't let three banks tell you no and assume that's the answer. The first three banks looked at my tax returns. I looked at my actual business. That's the difference.'
If you're self-employed in Washington a business owner, a freelancer, a 1099 contractor, a consultant and you've been told your income 'doesn't qualify,' let's look at your actual cash flow before you give up. There's a good chance the right program exists for you.
Is a Bank Statement Loan Right for You?
Bank statement loans aren't for everyone. They're designed for self-employed borrowers whose tax returns don't reflect their real earning power. If you have W-2 income, a conventional loan will almost always be cheaper.
But if you're a business owner, independent contractor, or freelancer in Pierce County or anywhere in Washington, and you've been denied because of 'low income' on your tax returns, a bank statement loan may be the path that gets you home.
All loan products, interest rates, and terms are subject to credit approval and market conditions. This is not a commitment to lend. Programs, rates, terms, and conditions are subject to change without notice.
Have questions about your mortgage?
Book a free 15-minute call with Peter no credit pull required.
Related Articles
DSCR Loans for Real Estate Investors in Pierce County: No Income Docs Required
How DSCR loans help Pierce County investors qualify on rental income instead of tax returns ideal for self-employed buyers growing a portfolio.
Self-Employed in Washington? You Can Still Get a Mortgage Without Tax Returns
Bank statement loans and other non-QM options let self-employed Washington business owners qualify on cash flow instead of tax returns. Here's how it works.
No Social Security Number, No Problem: How a Tacoma Family Bought a Home with an ITIN Mortgage
You don't need a Social Security number to buy a home in Washington. Here's how one Tacoma family who files taxes with an ITIN achieved homeownership.