
No Social Security Number, No Problem: How a Tacoma Family Bought a Home with an ITIN Mortgage
Reviewed by Peter Irungu, NMLS #2751063 | Last updated October 23, 2026
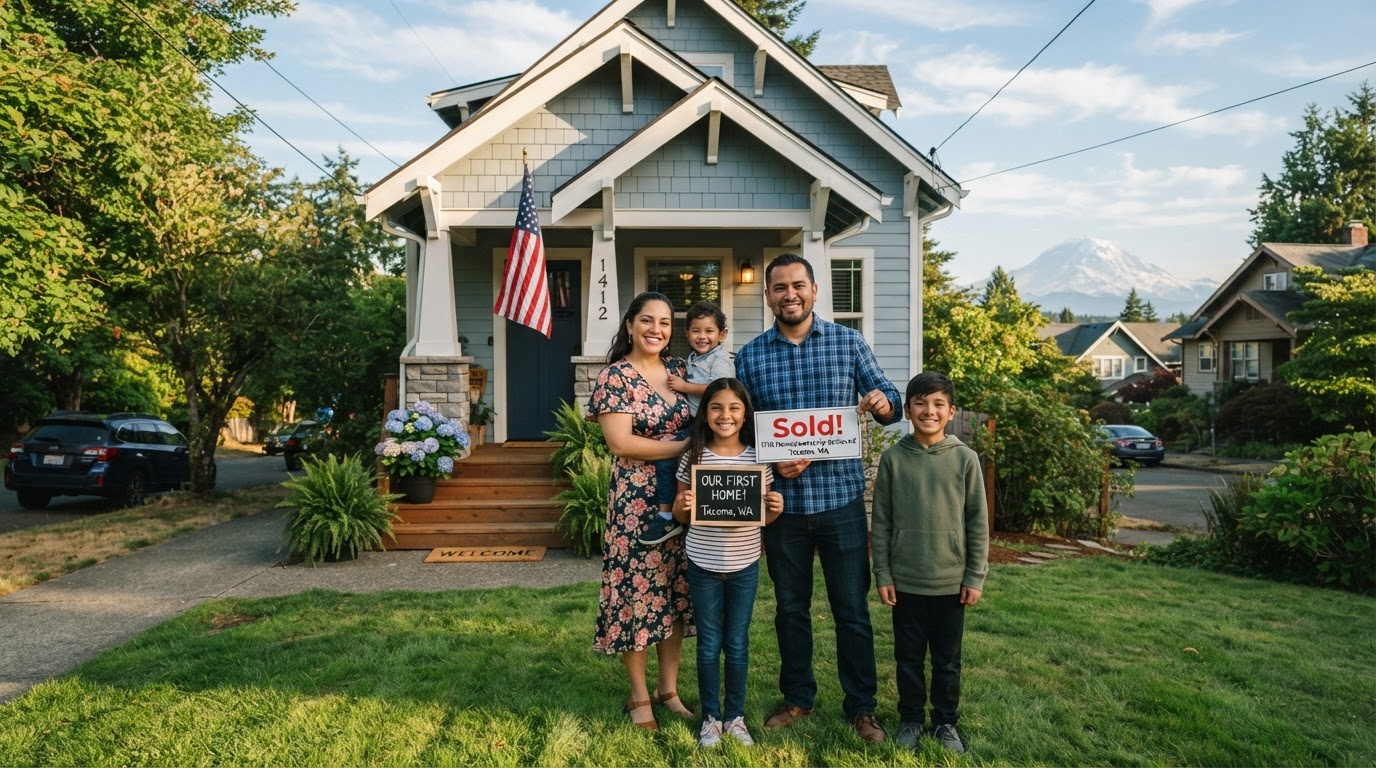
Carlos and Elena had lived in Tacoma for nine years. Carlos worked in construction, Elena cleaned homes, and together they saved enough for a down payment on a small house. They filed taxes every year with an Individual Taxpayer Identification Number (ITIN) the number the IRS issues to people who need to file taxes but don't qualify for a Social Security number.
Every time they tried to get a mortgage, the answer was the same: 'We can't lend without a Social Security number.' Then a friend told them about ITIN mortgages home loans designed specifically for borrowers who file taxes with an ITIN. They called me, unsure if it was real. It is. Here's how we helped Carlos and Elena buy their first home in Tacoma's South End.
What Is an ITIN Mortgage and Who Is It For?
An ITIN mortgage is a home loan designed for borrowers who have an Individual Taxpayer Identification Number (ITIN) instead of a Social Security number. ITINs are issued by the IRS to foreign nationals and others who need to file taxes but don't qualify for a Social Security number. If you file taxes with an ITIN, pay your bills on time, and have stable income, an ITIN mortgage can make homeownership possible.
It's important to understand who this product is and isn't for. Lawful Permanent Residents green card holders have Social Security Numbers and qualify for FHA, VA, and conventional loans just like U.S. citizens. ITIN mortgages are specifically for borrowers who don't have an SSN and instead use an ITIN to file and pay taxes.
ITIN mortgages are non-QM (non-qualified mortgage) products, which means they don't follow the same underwriting rules as conventional, FHA, or VA loans. They're offered by specialized lenders and portfolio lenders who hold the loans rather than selling them to Fannie Mae or Freddie Mac. Carlos and Elena qualified for a $365,000 loan on a home in Tacoma's South End a neighborhood they'd been renting in for years.
What Carlos and Elena Needed to Qualify
The documentation for an ITIN mortgage is different from a conventional loan, but it's not harder it's just different. Carlos and Elena provided: their ITIN letters from the IRS, two years of tax returns filed with their ITINs, proof of income (Carlos's construction pay stubs and Elena's cleaning business deposits), bank statements showing their savings, and a valid government-issued ID.
The credit requirement was met through an alternative credit history we built a credit profile using their rent payments, utility bills, and other recurring obligations. Many ITIN lenders use alternative credit scoring rather than traditional FICO scores.
The down payment was 20% higher than a conventional or FHA loan, but manageable because Carlos and Elena had been saving for five years. Their interest rate was higher than a conventional rate, which is typical for ITIN mortgages. But for a family that had been told 'no' by every bank in town, the ability to buy at all was life-changing.
The Process and the Timeline
From application to closing, Carlos and Elena's ITIN mortgage took about 45 days longer than a conventional loan but faster than they expected. The appraisal came in at value, the underwriting was thorough but fair, and the closing went smoothly.
Their monthly payment including taxes and insurance was about $2,650. Their previous rent had been $1,950. The difference was $700 per month but they were building equity in a home they owned, not paying their landlord's mortgage.
Carlos called me the week after they moved in. 'My kids have their own rooms,' he said. 'Elena is crying every day because she can't believe this is ours.' That's what ITIN mortgages make possible.
Is an ITIN Mortgage Right for You?
ITIN mortgages aren't for everyone. They typically require 15-20% down, have higher rates than conventional loans, and are available through fewer lenders. But if you file taxes with an ITIN, have stable income, and have been told you can't buy a home because you don't have a Social Security number, an ITIN mortgage may be your path to homeownership.
If you're a green card holder or have a Social Security number, you likely qualify for FHA, VA, or conventional loans with lower down payments and lower rates an ITIN mortgage isn't the right fit for you. The right program depends on your immigration status, your income, your down payment savings, and the property you're buying.
I'll review your situation and help you understand what's available in whatever language is most comfortable for you and your family.
All loan products, interest rates, and terms are subject to credit approval and market conditions. This is not a commitment to lend. ITIN mortgage availability and requirements vary by lender. Programs, rates, terms, and conditions are subject to change without notice.
Have questions about your mortgage?
Book a free 15-minute call with Peter no credit pull required.
Related Articles
Self-Employed in Washington? You Can Still Get a Mortgage Without Tax Returns
Bank statement loans and other non-QM options let self-employed Washington business owners qualify on cash flow instead of tax returns. Here's how it works.
The Restaurant Owner Who Couldn't Get a Mortgage Until We Looked at Her Bank Statements
How a Pierce County restaurant owner went from 'denied by three banks' to closing on her first home using a bank statement loan.
Retired with Assets but No W-2: How a Pierce County Retiree Qualified for a Mortgage Using Asset Depletion
When your income is in investments, not paychecks, qualifying for a mortgage can feel impossible. Here's how asset depletion qualification helped one retiree buy a home in Lakewood.