
The Retired Teacher Who Stayed in Her Tacoma Home: A Reverse Mortgage Story
Reviewed by Peter Irungu, NMLS #2751063 | Last updated October 23, 2026
Carol taught second grade in Tacoma for 34 years. She'd lived in the same craftsman home near Point Defiance since 1994, raised her kids there, and planned to stay for the rest of her life. But by 2026, at 68 years old, she was facing a problem: her pension and Social Security covered her living expenses, but her $1,650 monthly mortgage payment was eating into a budget that had no room to spare.
Her daughter, concerned, suggested selling and downsizing. Carol didn't want to leave. That's when they came to me to explore whether a reverse mortgage could be the answer. Here's how it worked and why it let Carol stay in the home she loved.
What Carol Was Really Facing
Carol's home was worth about $580,000. She owed $145,000 on her existing mortgage, with 11 years left on a 30-year loan at 4.25%. Her monthly payment of $1,650 represented nearly 40% of her monthly retirement income.
She wasn't behind on payments. She wasn't in crisis. But she was uncomfortable and getting more so each year as property taxes and insurance rose while her pension stayed flat. Her daughter's suggestion to sell made financial sense on paper, but it ignored something that didn't fit in a spreadsheet: this was home.
A reverse mortgage specifically, a Home Equity Conversion Mortgage (HECM) offered a different path. Instead of selling, Carol could pay off her existing mortgage with the reverse mortgage, eliminating her monthly payment entirely while staying in her home.
How the HECM Worked for Carol
At 68, with a home valued at $580,000, Carol qualified for a HECM that provided enough to pay off her existing $145,000 mortgage and cover the closing costs. The remaining equity stayed in her home she didn't give up ownership, and she didn't sell the house to a bank.
Here's what changed: her $1,650 monthly mortgage payment disappeared. Instead of paying the bank, the loan balance grew over time as interest accrued. But because a HECM is a non-recourse loan insured by the FHA, Carol or her heirs would never owe more than the home was worth when the loan was repaid.
She still owned her home. She still paid property taxes and insurance. She still maintained the property. But the monthly burden that was squeezing her retirement budget was gone.
The Counseling Requirement and Why It Mattered
Before Carol could proceed, she completed a session with a HUD-approved housing counselor a mandatory step for every HECM borrower. The counselor walked her through the loan terms, the obligations, the alternatives, and the impact on her estate.
Carol told me later that the counseling session was the most valuable part of the process. 'It wasn't a sales pitch,' she said. 'It was someone whose only job was to make sure I understood what I was doing. That mattered.'
That's the point of the counseling requirement. A reverse mortgage is a powerful tool, but it's not right for everyone. The counseling ensures you understand the trade-offs before you commit and for Carol, it confirmed that the decision was the right one.
What Carol's Heirs Needed to Know
Carol's daughter had questions about what happens when Carol eventually passes away or moves out. The answer: the loan becomes due, and the heirs have options. They can sell the home and use the proceeds to pay off the loan (keeping any remaining equity). They can refinance the loan into their own name if they want to keep the home. Or they can deed the home back to the lender.
Because the HECM is non-recourse, if the loan balance exceeds the home's value at repayment, the heirs owe only what the home is worth the FHA insurance covers the difference. Carol's daughter wouldn't be on the hook for a debt she couldn't repay.
For Carol, the trade-off was worth it. She gave up some of the equity she'd built over 30 years but she gained the ability to stay in her home, on her terms, without a monthly payment she couldn't comfortably afford.
Is a Reverse Mortgage Right for You?
A reverse mortgage isn't a one-size-fits-all solution. It's a tool one that makes sense for some homeowners 62 and older and doesn't for others. The right answer depends on your home equity, your retirement income, your goals for your estate, and how long you plan to stay.
If you're 62+, have significant equity, and want to stay in your home without a monthly mortgage payment, it may be worth exploring. If you're planning to sell within a few years, or if you want to preserve all your equity for your heirs, it may not be the right fit.
NEXA Lending, LLC is a private mortgage company and is not affiliated with, endorsed by, or acting on behalf of HUD, FHA, or any government agency. HECM borrowers must complete HUD-approved counseling. This is not a commitment to lend. All loan products, rates, and terms are subject to credit approval and market conditions.
Have questions about your mortgage?
Book a free 15-minute call with Peter no credit pull required.
Related Articles
Reverse Mortgage Myths Debunked: What WA Homeowners 62+ Need to Know
Separating fact from fiction on reverse mortgages including the truth about ownership, repayment, and whether you can lose your home.
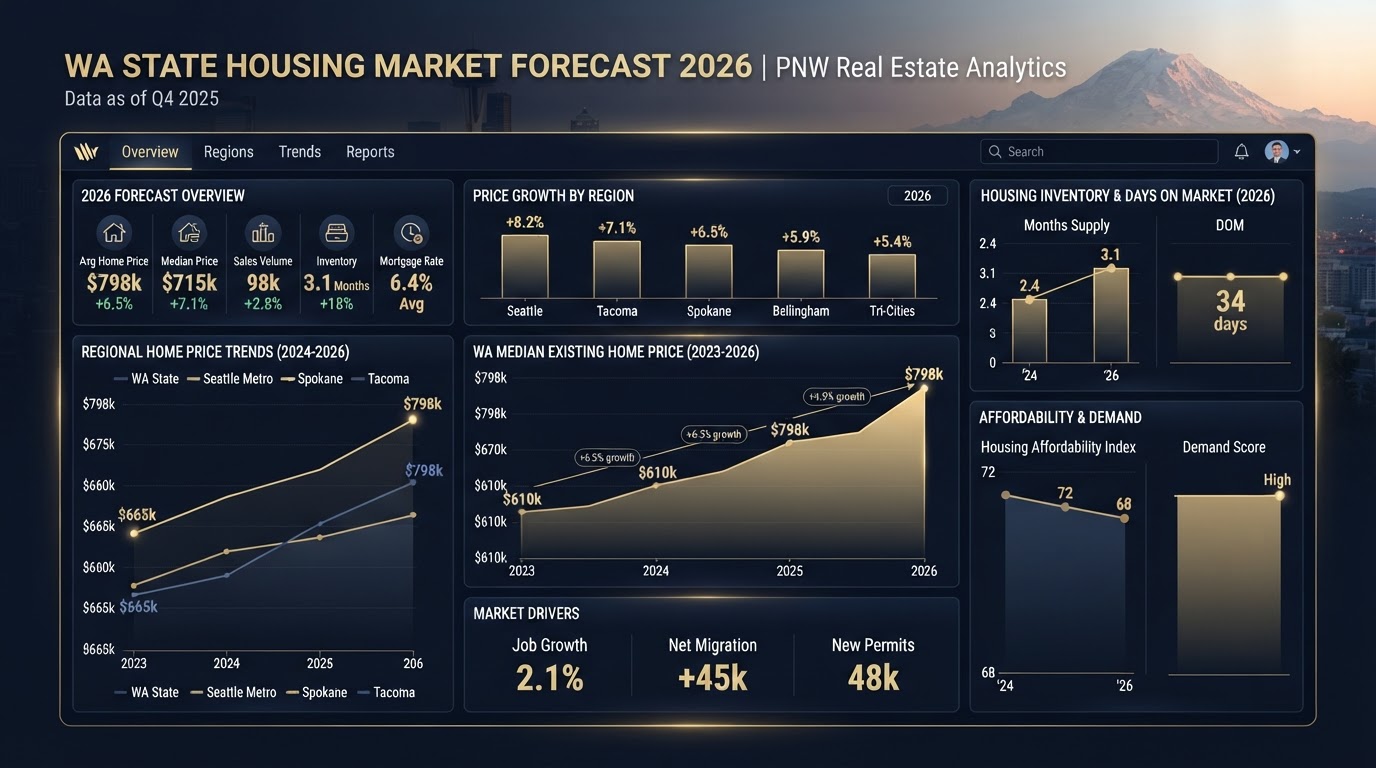
Washington Housing Market 2026: What Buyers and Investors Should Watch
Pierce County and King County trends, interest rate outlook, and what it all means for your next home purchase or investment in 2026.
What Credit Score Do You Really Need for a Mortgage in Washington?
The minimums aren't the whole story. Here's how your credit score actually affects your rate, your options, and your monthly payment in Washington.