
What Credit Score Do You Really Need for a Mortgage in Washington?
Reviewed by Peter Irungu, NMLS #2751063 | Last updated October 23, 2026
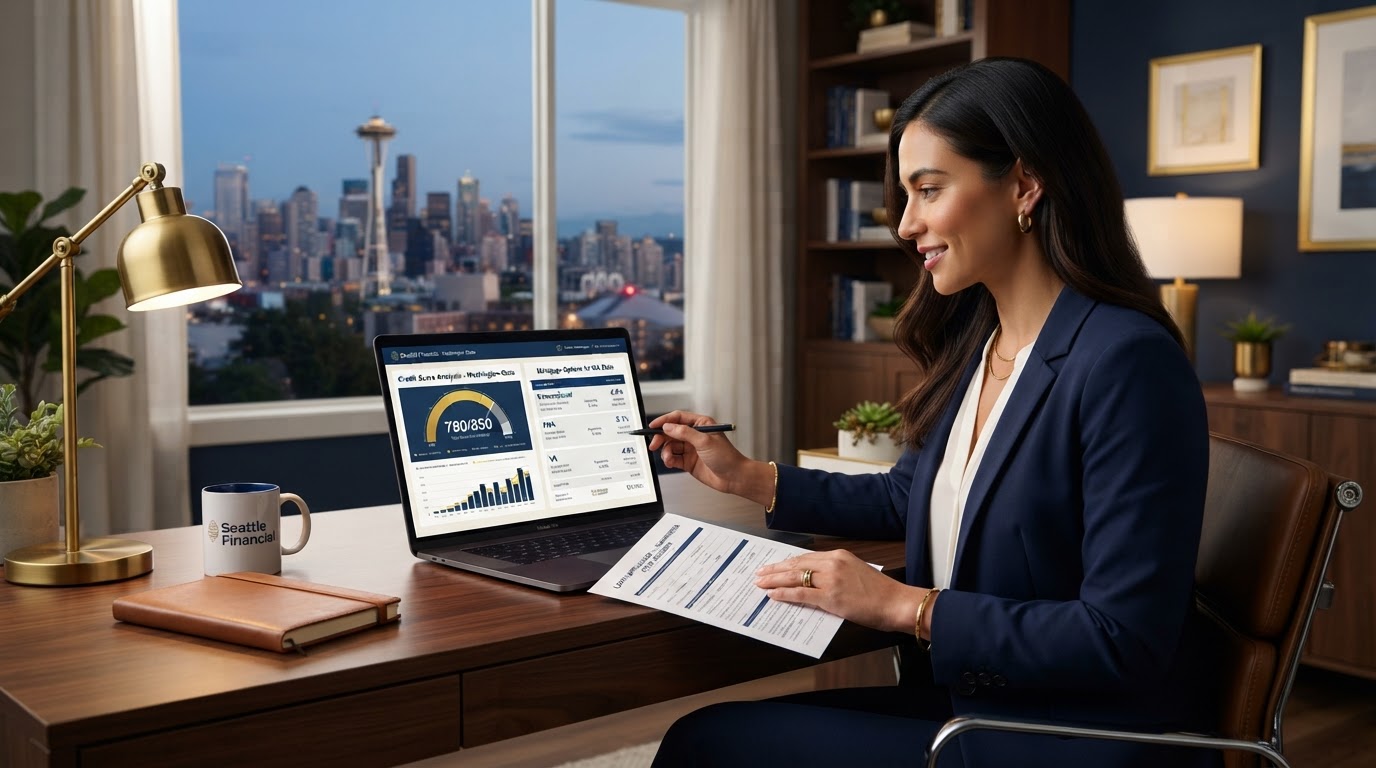
What credit score do you need to buy a home in Washington? The short answer is: it depends on the loan. The more useful answer is: your score does more than just get you in the door it shapes your rate, your options, and your monthly payment for years to come.
Let me walk you through what actually matters.
The Minimums by Loan Type
FHA loans allow credit scores starting at 580 for the 3.5% down payment option. Conventional loans typically require 620 or higher. VA loans have no VA-mandated minimum, but lenders often set their own floor (often 580-620). USDA loans generally require 640+.
But these are just the minimums. The real question is what rate and terms you qualify for at your score.
Why Higher Scores Save You Money
Above the minimums, higher credit scores unlock better rates. A borrower at 740 may qualify for a meaningfully lower rate than a borrower at 660, even on the same loan program. Over 30 years, that difference can add up to tens of thousands of dollars.
I'll show you exactly how your score affects your rate and payment, and if there are quick wins to improve your score before you apply, I'll point them out.
What If Your Score Is Below 580?
If your score is below 580, FHA may still be an option with 10% down. There are also credit-building strategies that can raise your score in months, not years. Sometimes paying down a single credit card can boost your score by 20-40 points.
Don't assume you're disqualified. Let me look at your full picture and find the fastest path to qualification.
Credit Myths That Cost Buyers
Myth: Checking your credit hurts your score. Fact: Checking your own credit (a soft pull) has zero impact. Myth: You need perfect credit to buy a home. Fact: Most of my buyers have scores in the 600s. Myth: Paying off collections always helps. Fact: Sometimes it can temporarily lower your score.
I've seen buyers with scores in the low 600s get approved and buyers with 780 scores get denied for other reasons. Your score is one piece of the puzzle, not the whole picture.
Have questions about your mortgage?
Book a free 15-minute call with Peter no credit pull required.
Related Articles
Reverse Mortgage Myths Debunked: What WA Homeowners 62+ Need to Know
Separating fact from fiction on reverse mortgages including the truth about ownership, repayment, and whether you can lose your home.
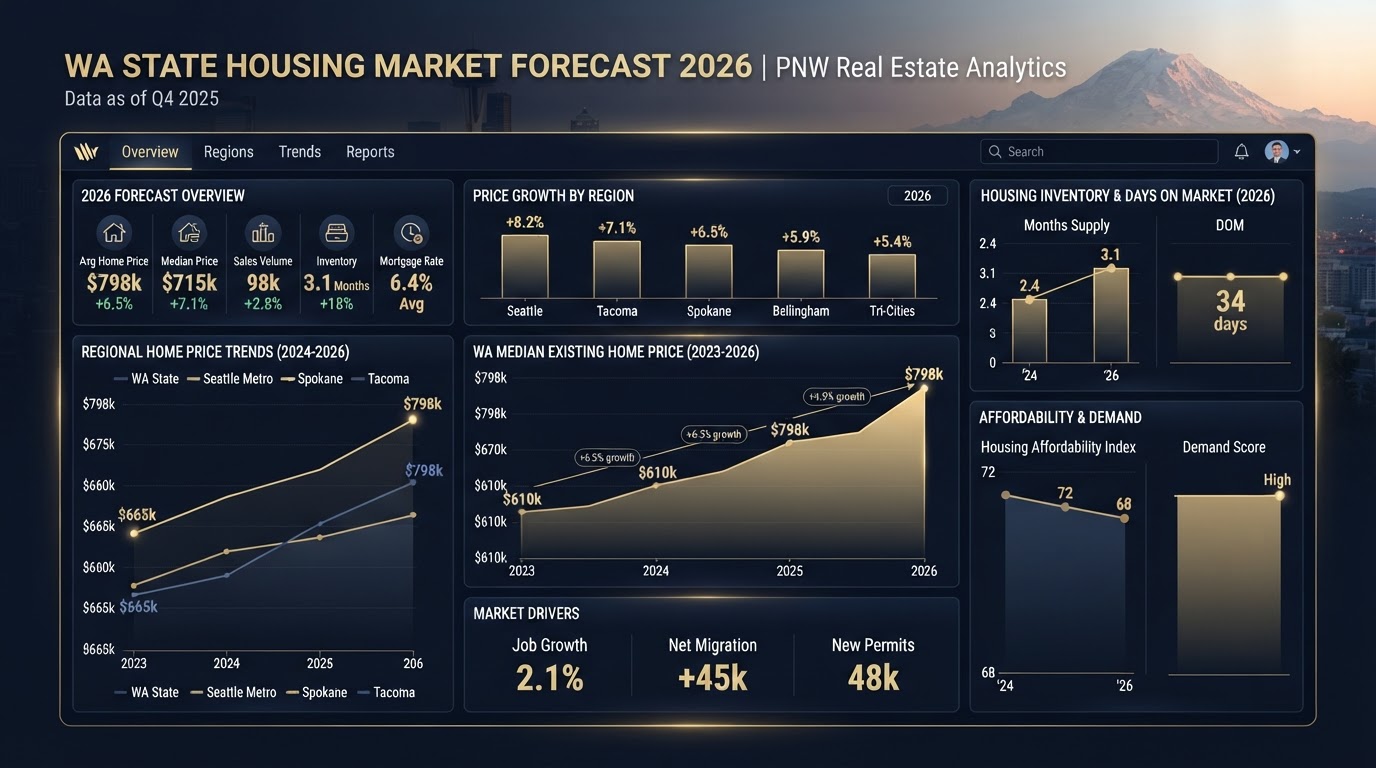
Washington Housing Market 2026: What Buyers and Investors Should Watch
Pierce County and King County trends, interest rate outlook, and what it all means for your next home purchase or investment in 2026.
The Retired Teacher Who Stayed in Her Tacoma Home: A Reverse Mortgage Story
How a 68-year-old retired educator used a reverse mortgage to eliminate her mortgage payment and stay in the Tacoma home she'd lived in for 30 years.