
Should You Refinance Your Washington Home in 2026? A Honest Breakdown
Reviewed by Peter Irungu, NMLS #2751063 | Last updated October 23, 2026
If you bought your Washington home in the last few years, you might be wondering whether refinancing makes sense. Maybe rates have dropped since you closed. Maybe you want to tap your equity for renovations. Or maybe you're just not sure if the timing is right.
The honest answer is: it depends. Let me walk you through how to decide.
The Break-Even Test
The simplest way to evaluate a refinance is the break-even calculation. Take your total closing costs and divide by your monthly savings. If it costs $4,000 to refinance and you save $200 per month, your break-even is 20 months. If you plan to stay in the home longer than that, refinancing makes sense.
I'll run this calculation for your specific loan so you can see exactly when you'd start saving money. No guesswork, just the math.
Rate-and-Term vs. Cash-Out
A rate-and-term refinance replaces your current loan with a new one at a better rate or term, with no cash out. A cash-out refinance lets you pull equity from your home as cash, which you can use for renovations, debt consolidation, or investment.
Each has different costs, qualification requirements, and long-term implications. I'll help you compare both options side by side.
Don't Forget About HELOCs
If you just want to access equity without replacing your first mortgage, a Home Equity Line of Credit (HELOC) might be a better fit. You keep your current rate and only draw on the line when you need it.
For some homeowners, a HELOC is the smarter move. For others, a full refinance saves more over time. Let's compare both and see which one fits your goals.
When Waiting Makes Sense
Sometimes the right answer is to wait. If you're planning to sell within a year or two, the closing costs of a refinance may not pay off. If your current rate is already competitive, the savings may not justify the expense.
I'll give you an honest assessment even if that means telling you to wait. My job is to help you make the right financial decision, not to push a loan you don't need.
Have questions about your mortgage?
Book a free 15-minute call with Peter no credit pull required.
Related Articles
HELOC or Cash-Out Refinance? How Washington Homeowners Should Choose
Two ways to tap your home equity, two very different outcomes. Here's how to decide between a HELOC and a cash-out refinance with real numbers and real trade-offs.
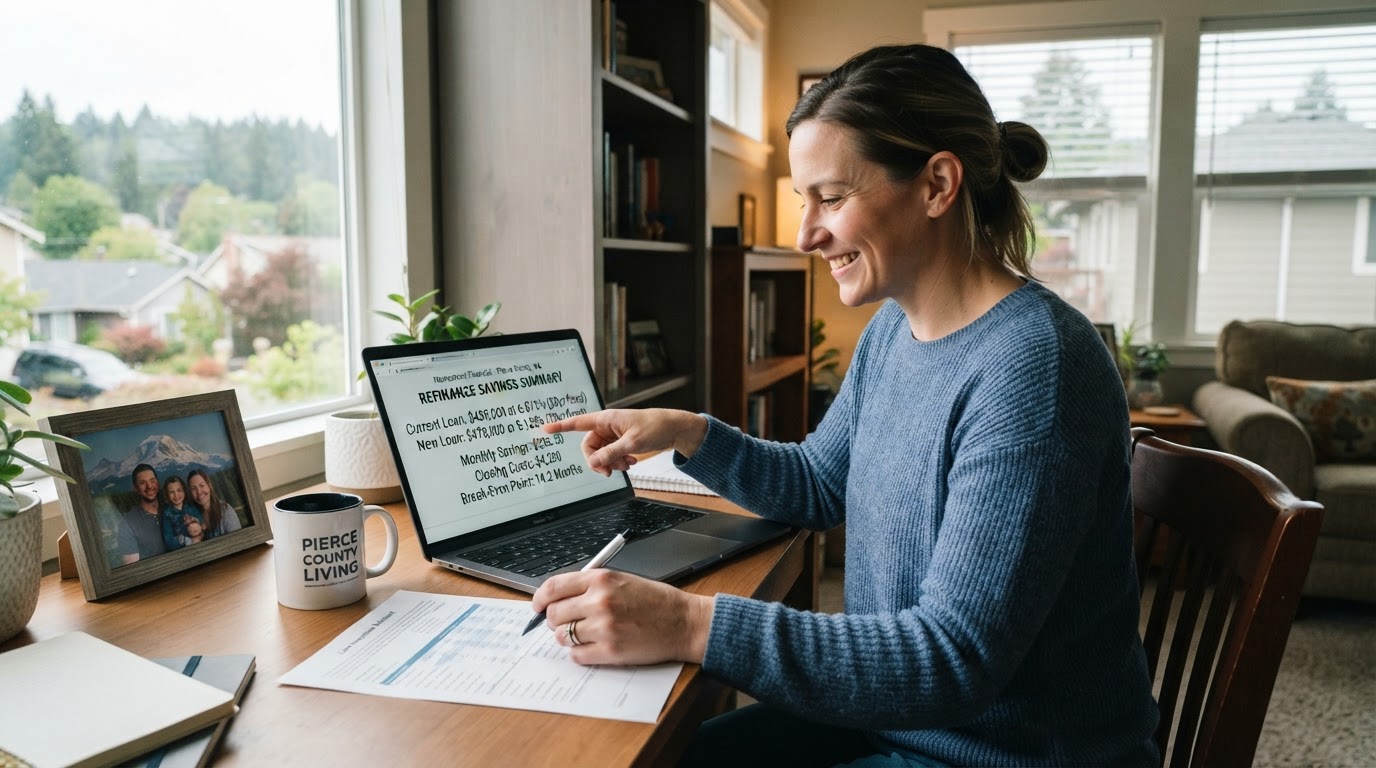
From 6.875% to 5.375%: How a Pierce County Homeowner Saved $380 a Month with a Rate-and-Term Refinance
A real look at the numbers behind a rate-and-term refinance in Washington the break-even calculation, the closing costs, and the monthly savings that made it worth it.
From Outdated to Updated: How a Pierce County Homeowner Funded a $60,000 Renovation with a Cash-Out Refinance
Their home had the space they needed but not the look they wanted. Here's how one couple used a cash-out refinance to fund a major renovation and whether it was the right move.