
From 6.875% to 5.375%: How a Pierce County Homeowner Saved $380 a Month with a Rate-and-Term Refinance
Reviewed by Peter Irungu, NMLS #2751063 | Last updated October 23, 2026
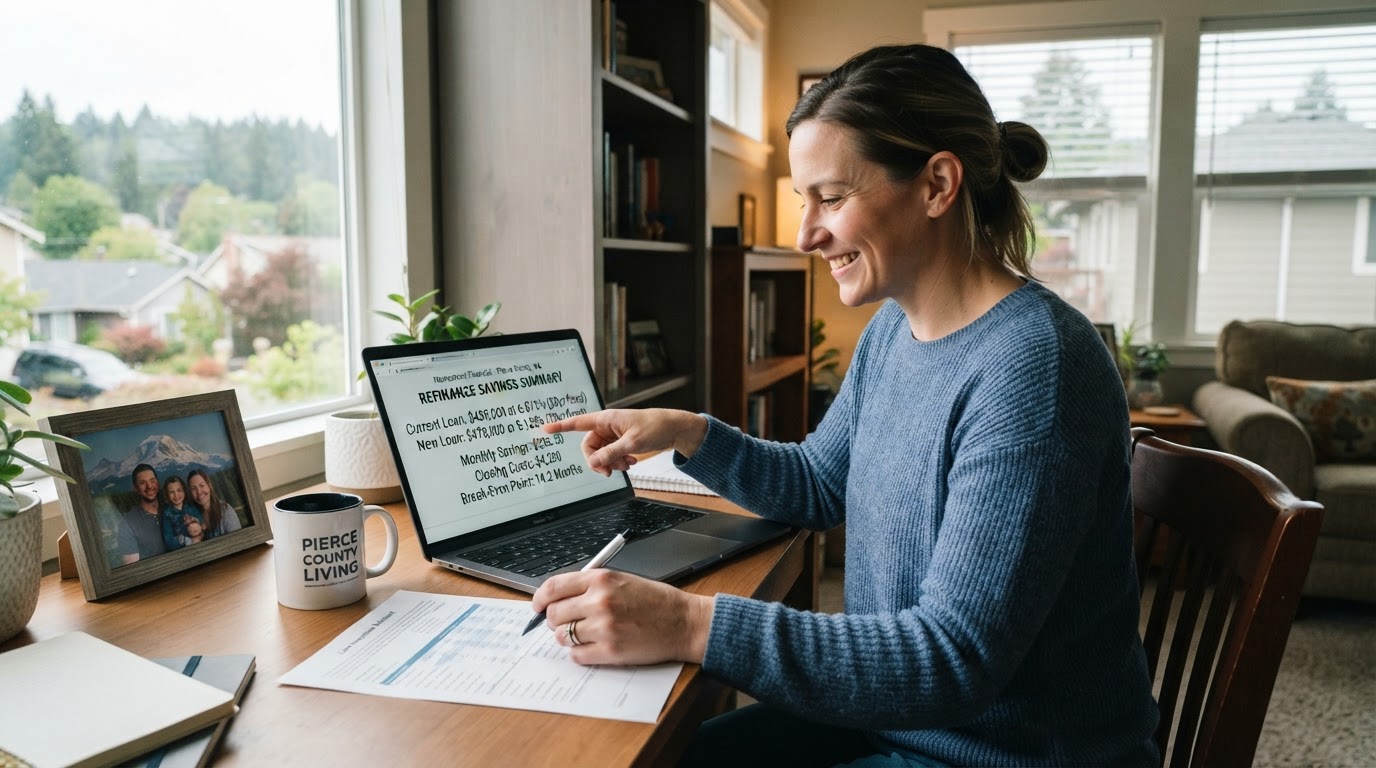
Tom bought his home in Puyallup in 2023 at 6.875%. By mid-2026, rates had dipped enough that refinancing started to make sense. But Tom wasn't sure he'd heard that you need to drop your rate by a full percentage point to make refinancing 'worth it,' and his rate improvement was only about 1.5 points.
He called me to run the numbers. Here's the actual math behind his refinance decision and why the old '1% rule' doesn't tell the whole story.
The Break-Even Calculation That Actually Matters
Tom's existing loan: $384,000 at 6.875% with 27 years remaining. His monthly principal and interest payment was $2,518. His refinance rate: 5.375% with 27 years remaining. New monthly payment: $2,138. Monthly savings: $380.
His closing costs for the refinance: about $4,200 (including title, escrow, and lender fees). Break-even: $4,200 divided by $380 per month = about 11 months. If Tom planned to stay in the home for more than 11 months, the refinance paid for itself and then some.
The old '1% rule' (refinance only if your rate drops by a full point) is oversimplified. The real question is: how long will it take for the monthly savings to cover the closing costs? If your break-even is under 2 years and you plan to stay 5+ years, refinancing almost always makes sense even with a smaller rate drop.
Why Tom Didn't Reset His Term
Tom had 27 years left on his original 30-year loan. He could have refinanced into a new 30-year loan and lowered his payment even further but that would have added 3 years of payments to the back end of his loan. Instead, he kept the 27-year term, which meant his savings came entirely from the rate reduction, not from stretching out the loan.
This is an important distinction. A lower payment from a longer term isn't true savings you're paying less per month but more over the life of the loan. A lower payment from a lower rate is real savings. Tom's $380 monthly savings was genuine because he kept the same remaining term.
If you're considering a refinance, ask your lender to show you both scenarios: same remaining term vs. new 30-year term. The difference in total interest paid over the life of the loan can be significant.
The Appraisal and the Process
Tom's home appraised at $510,000 up from his purchase price of $460,000 three years earlier. His loan-to-value ratio was 75%, well under the 80% threshold that eliminates the need for mortgage insurance on a conventional refinance.
The refinance process took 28 days from application to closing faster than Tom's original purchase because there was no seller or real estate agent involved. The appraisal was ordered immediately, underwriting was straightforward, and Tom signed his closing documents at a title company in Tacoma.
His first payment on the new loan was due about 45 days after closing, giving him a one-month gap with no mortgage payment a nice side benefit of refinancing that many borrowers don't expect.
When Refinancing Doesn't Make Sense
Tom's refinance was a clear win. But not every refinance makes sense. If you're planning to sell within 1-2 years, the closing costs may not be recouped. If your current rate is already competitive, the savings may not justify the cost. And if you're in a 3% rate from 2020-2021, refinancing into today's rates would increase your payment don't do it.
The honest answer is: it depends on your rate, your remaining term, your home value, and how long you plan to stay. I'll run the break-even calculation for your specific loan so you can see exactly when you'd start saving and whether refinancing is the right move for you.
All loan products, interest rates, and terms are subject to credit approval and market conditions. This is not a commitment to lend. Programs, rates, terms, and conditions are subject to change without notice.
Have questions about your mortgage?
Book a free 15-minute call with Peter no credit pull required.
Related Articles
Should You Refinance Your Washington Home in 2026? A Honest Breakdown
Rate-and-term, cash-out, or wait it out? Here's how Washington homeowners can decide whether refinancing makes financial sense right now.
HELOC or Cash-Out Refinance? How Washington Homeowners Should Choose
Two ways to tap your home equity, two very different outcomes. Here's how to decide between a HELOC and a cash-out refinance with real numbers and real trade-offs.
From Outdated to Updated: How a Pierce County Homeowner Funded a $60,000 Renovation with a Cash-Out Refinance
Their home had the space they needed but not the look they wanted. Here's how one couple used a cash-out refinance to fund a major renovation and whether it was the right move.