
The Rate Buydown Trick: How a Pierce County Buyer Got a 4.99% Rate in a 6.5% Market
Reviewed by Peter Irungu, NMLS #2751063 | Last updated October 23, 2026
When rates hovered around 6.5% in the summer of 2026, most Pierce County buyers assumed they were stuck. They'd watched rates climb from the 3% days and resigned themselves to either waiting possibly forever or accepting a payment that stretched their budget thin.
But Kevin and Lisa didn't wait. They bought a $520,000 home in Puyallup and locked in a 4.99% rate for the first year not by paying points themselves, but by asking the seller to pay for a rate buydown as part of their offer. Here's how it works and why more Washington buyers should be using it.
What Is a Rate Buydown
A rate buydown is a seller-paid concession that temporarily lowers your interest rate for the first few years of your mortgage. The seller pays a lump sum upfront to the lender, and that money is used to subsidize your monthly payment for a set period usually one, two, or three years.
The most common structure is a 2-1 buydown. In year one, your rate is 2% below the note rate. In year two, it's 1% below. In year three and beyond, it returns to the full rate. On Kevin and Lisa's loan, the note rate was 6.5%. Year one: 4.99%. Year two: 5.99%. Year three: 6.5%.
The cost to the seller in their case, about $9,800 was far less than the price reduction they would have had to accept to make the home affordable. And for Kevin and Lisa, the savings were immediate and real: their year-one payment was $460 lower than it would have been at the full rate.
Why Sellers Agree to It
In a buyer's market or a flat market, sellers are motivated to make deals work without slashing their asking price. A $10,000 rate buydown costs the seller less than a $20,000 price reduction and it often makes the monthly payment more affordable for the buyer than a price cut would, because the savings compound over the life of the loan.
Kevin and Lisa's seller had been on the market for 47 days. They'd already reduced the price once. A rate buydown let them keep their asking price intact while giving the buyers a payment they could afford. It was a win for both sides.
Rate buydowns also work in refinance transactions. If you're refinancing and your lender offers a buydown option, the cost can sometimes be rolled into the loan though that increases your balance, so it's worth comparing carefully.
The Math That Matters
Here's what the numbers looked like for Kevin and Lisa. Purchase price: $520,000. Down payment: 10% ($52,000). Loan amount: $468,000. Note rate: 6.5%. Monthly payment at full rate: about $2,960 for principal and interest.
With the 2-1 buydown: year one payment was about $2,500. Year two: about $2,730. Year three and beyond: $2,960. Over the first two years, they saved roughly $9,960 in payments almost exactly what the seller paid for the buydown. The savings were front-loaded when they needed them most: right after buying, when money is tightest.
The key question to ask: what happens in year three? Your payment goes up. You need to plan for that. Kevin and Lisa knew their incomes would grow, and they planned to refinance if rates dropped. But if you're already stretched at the full rate, a buydown just delays the problem it doesn't solve it.
When a Buydown Makes Sense and When It Doesn't
A rate buydown makes sense when you're buying in a market where sellers are willing to negotiate, you can afford the full-rate payment but want breathing room in the early years, and you expect your income to grow or rates to fall. It's a bridge, not a permanent fix.
It doesn't make sense if you can't afford the payment at the full rate. If year three's payment would break your budget, you're buying more house than you can handle and a buydown just hides that until it becomes a crisis.
It also doesn't make sense if the seller charges you for the buydown by raising the price. Some sellers will offer a buydown but only if you pay full asking. In that case, you're paying for your own savings. I'll always run both scenarios so you can see the real cost.
I can structure a buydown offer for you and show the seller's agent exactly what it costs them versus a price reduction. Often, the buydown is the cheaper path for everyone. This is not a commitment to lend. Rates and terms vary based on credit, loan type, and market conditions.
Have questions about your mortgage?
Book a free 15-minute call with Peter no credit pull required.
Related Articles
Reverse Mortgage Myths Debunked: What WA Homeowners 62+ Need to Know
Separating fact from fiction on reverse mortgages including the truth about ownership, repayment, and whether you can lose your home.
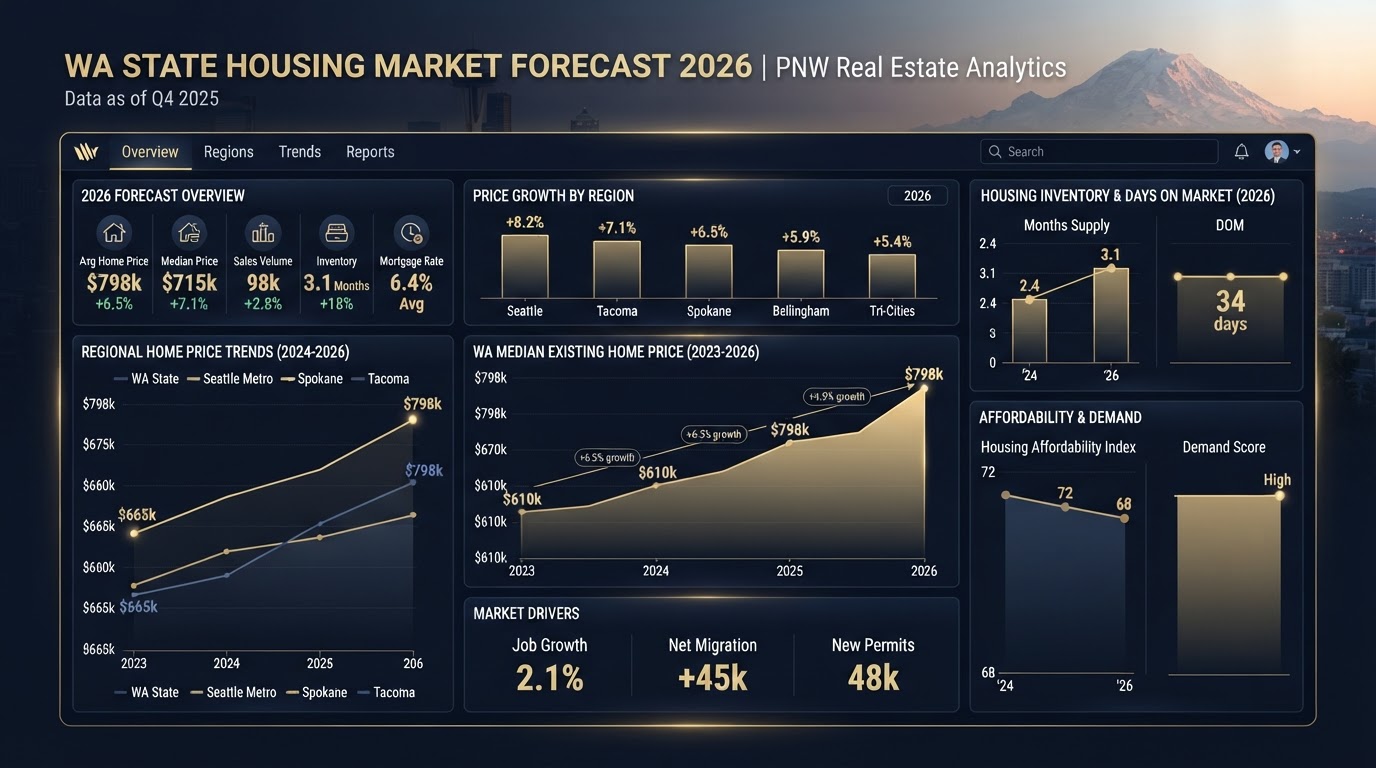
Washington Housing Market 2026: What Buyers and Investors Should Watch
Pierce County and King County trends, interest rate outlook, and what it all means for your next home purchase or investment in 2026.
What Credit Score Do You Really Need for a Mortgage in Washington?
The minimums aren't the whole story. Here's how your credit score actually affects your rate, your options, and your monthly payment in Washington.