
Zero Down in the Country: How a Young Family Bought a Home Outside Puyallup with a USDA Loan
Reviewed by Peter Irungu, NMLS #2751063 | Last updated October 23, 2026
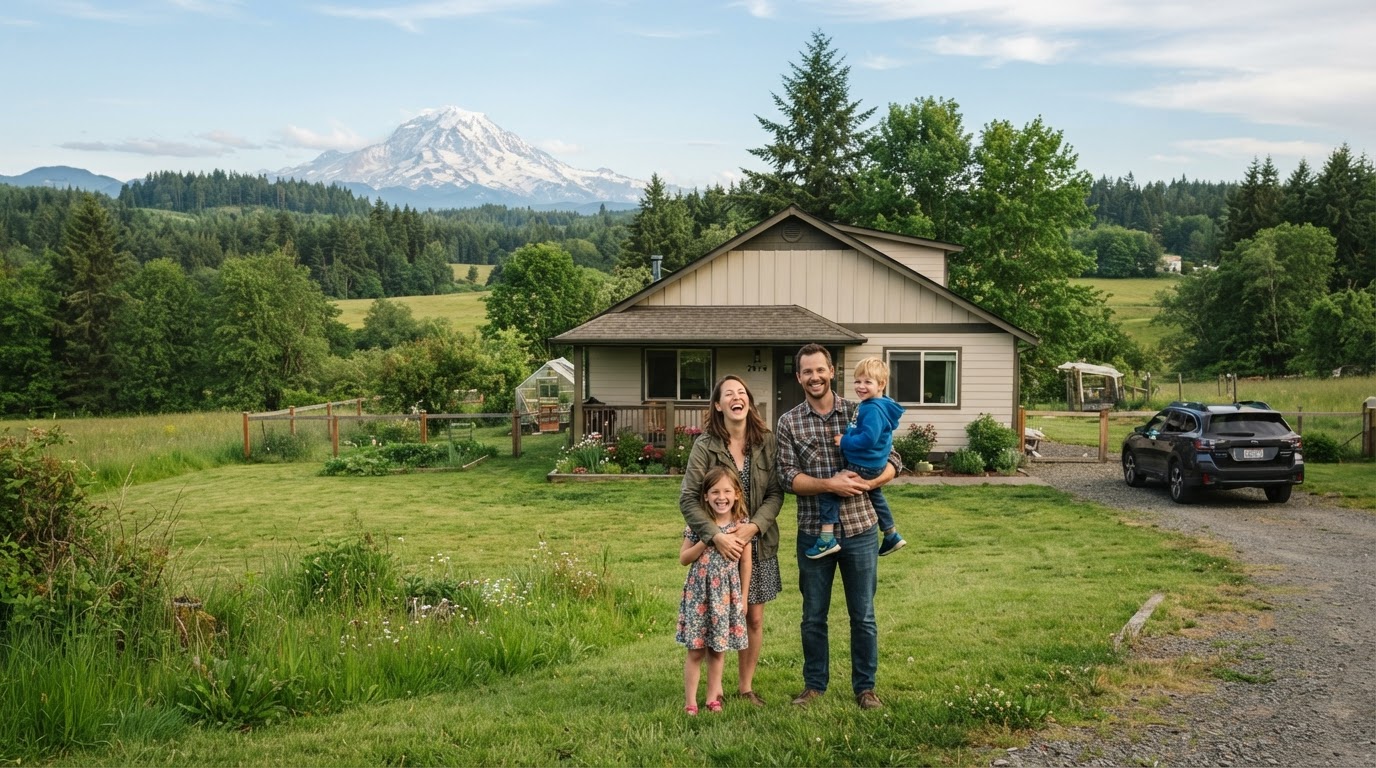
Tyler and Megan were both 27, newly married, and tired of renting a duplex in Puyallup while watching home prices climb. Their combined income was solid about $95,000 but they'd only managed to save $12,000. In Pierce County, that wasn't enough for a conventional down payment plus closing costs on anything they'd actually want to live in.
Then a friend mentioned USDA loans. Tyler called me skeptical: 'A government loan for buying a house? That sounds too good to be true.' It's not a government loan exactly it's a government-guaranteed loan made through approved private lenders. And for buyers willing to look outside the city limits, it can be the difference between renting another year and owning a home.
Here's how Tyler and Megan bought a three-bedroom home on a half-acre in Graham 12 miles south of Puyallup with zero down payment.
What Makes a USDA Loan Different
A USDA Rural Development loan is designed for buyers purchasing homes in eligible rural and suburban areas. The key features: zero down payment, below-market fixed rates, and no PMI though there is an upfront guarantee fee that can be financed into the loan.
The catch? The property has to be in a USDA-eligible area, and there are household income limits based on your county and family size. For Tyler and Megan in Pierce County, the income limit was well above their $95,000 combined income, so they qualified comfortably.
USDA eligibility is based on the property's location, not the buyer's. You can live anywhere and buy a home in a USDA-eligible area you just have to be willing to look outside the densest city centers. In Pierce County, communities like Graham, Eatonville, Roy, and parts of Orting qualify. In King County, areas east of Snoqualmie and parts of the Snoqualmie Valley can qualify.
Finding the Right Home in Graham
Tyler and Megan started looking in Puyallup proper, but everything in their price range was a townhome or a fixer-upper that needed $50,000 in work. When I suggested expanding their search to Graham a 20-minute commute from Puyallup they found a three-bedroom, two-bath ranch on a half-acre lot listed at $395,000.
The home was in a USDA-eligible area. We ran the numbers: zero down payment meant their loan amount was the full purchase price plus the upfront guarantee fee. Their monthly payment including the USDA guarantee fee, property taxes, and insurance came to about $2,810 roughly $400 more than their rent, but building equity from day one.
The best part? Their $12,000 in savings covered their closing costs and left them with a small reserve. They didn't have to drain their accounts to get into a home.
The Income and Credit Requirements
USDA loans have household income limits meaning all income from all adults in the household counts, not just the borrowers. For Tyler and Megan, their $95,000 combined income was well under the Pierce County limit. But if Megan's mother had moved in and contributed income, that would have counted too.
On the credit side, USDA loans generally require a 640+ credit score, though some lenders have flexibility. Tyler's score was 685 and Megan's was 702 both comfortably above the threshold. Their debt-to-income ratio needed to be under 41%, and with their only debt being a $320 car payment, they were well within range.
One thing to know: USDA loans are for primary residences only. You can't use one to buy a second home or investment property. But for a family buying their first home in an eligible area, it's hard to beat zero down.
The Trade-Offs Worth Knowing
USDA loans aren't perfect for every situation. The upfront guarantee fee (1% of the loan amount in 2026) is financed into the loan, which increases your balance. There's also an annual fee (0.35% of the loan amount) that's paid monthly as part of your payment similar to mortgage insurance, but typically lower than FHA's monthly premium.
The bigger trade-off is location. If you want to live in downtown Puyallup or Tacoma, a USDA loan won't work those areas aren't eligible. You have to be willing to look at properties outside the city limits, which can mean a longer commute or fewer nearby amenities.
For Tyler and Megan, the trade-off was worth it. They got more house, more land, and a lower barrier to entry than any other loan program could offer. And when they're ready to move in five or ten years, they can sell, refinance, or keep the home as a rental the USDA loan doesn't restrict what you do with the property after you own it.
NEXA Lending, LLC is a private mortgage company and is not affiliated with, endorsed by, or acting on behalf of the USDA or any government agency. USDA property eligibility depends on the specific property address not all areas qualify. This is not a commitment to lend.
Have questions about your mortgage?
Book a free 15-minute call with Peter no credit pull required.
Related Articles
FHA vs Conventional Loans in Washington State: Which Is Right for You?
Comparing down payments, mortgage insurance, credit requirements, and costs to help Washington buyers choose between FHA and conventional financing.
7 First-Time Homebuyer Mistakes to Avoid in Washington State (And How to Dodge Them)
From underestimating closing costs to skipping the pre-approval, here are the most common first-time buyer mistakes in Washington and exactly how to avoid each one.
Condo vs. House in Washington: Which Is the Smarter First Purchase?
HOA fees, appreciation, maintenance, and lifestyle the real pros and cons of buying a condo versus a single-family home for Washington first-time buyers.