
Pre-Approved vs Pre-Qualified: The Difference That Cost One Pierce County Buyer Their Dream Home
Reviewed by Peter Irungu, NMLS #2751063 | Last updated October 23, 2026
Jasmine found the perfect house a three-bedroom craftsman in Puyallup's Maplewood neighborhood, listed at $445,000. She'd been browsing online for months and had a 'pre-qualification' letter from an online lender. She submitted an offer at full asking price.
She lost the house. The winning buyer offered $5,000 less but they had a full pre-approval letter from a local lender. The listing agent told Jasmine's agent: 'We don't accept pre-qualifications in a multiple-offer situation. Too many fall through.'
Here's the difference between pre-qualified and pre-approved and why it matters more than ever in Washington's competitive markets.
Pre-Qualified: A Quick Estimate
A pre-qualification is a soft estimate based on information you self-report your income, your debts, your assets without verification. No credit pull, no document review, no underwriting. It's essentially a lender saying 'based on what you told us, you might qualify for about this much.'
It's fast, it's free, and it's useful for getting a rough sense of your budget before you start shopping. But it carries almost no weight with sellers or listing agents, because nothing has been verified. You could tell the lender you make $100,000 and have $50,000 in savings, and they'll issue a pre-qualification based on that whether or not it's true.
Jasmine's online pre-qualification took about four minutes. She entered her income and estimated debts, and the system spat out a number. No documents were reviewed. No credit was pulled. It felt official it wasn't.
Pre-Approved: Verified and Underwritten
A pre-approval is a verified commitment from a lender. To get one, I'll review your actual documents: pay stubs, W-2s or tax returns, bank statements, and identification. I'll pull your credit a hard inquiry that shows your real scores and history. Then I'll run your file through underwriting to confirm you qualify for a specific loan amount at a specific rate.
The result is a pre-approval letter that says: this buyer has been reviewed, their income and assets are verified, their credit qualifies, and we will fund this loan subject to a satisfactory appraisal and property condition. That's the letter sellers and listing agents want to see.
It takes longer than a pre-qualification usually a day or two once I have your documents but it transforms you from a browser into a serious buyer. In a multiple-offer situation, a pre-approval can be the difference between winning and losing, even when your price isn't the highest.
What to Gather Before You Call
To get pre-approved efficiently, have these ready: your most recent 30 days of pay stubs, your last two years of W-2s or tax returns (including business returns if you're self-employed), two months of bank statements for all accounts, and a government-issued photo ID. If you have rental income, bring your lease agreements and tax Schedule E.
If you're self-employed, I'll need your business tax returns and a year-to-date profit and loss statement. The more complete your file, the faster I can issue a pre-approval and the stronger your offer looks.
One thing I won't ask for upfront: your Social Security number on a public web form. We handle credit pulls securely through the application portal after you've spoken with me. Your data is encrypted and never stored on the website.
How Strong Pre-Approval Wins Offers
Jasmine came back to me two weeks after losing the craftsman. We got her fully pre-approved verified income, verified assets, credit pulled, underwriting sign-off. Her pre-approval letter specified the loan amount, the loan type, and that her financing was confirmed subject only to appraisal.
Three weeks later, she found another home in Puyallup this time in a multiple-offer situation with four competing bids. She offered $3,000 above asking with her pre-approval letter and a clean inspection contingency. She won. The listing agent later told her agent that the pre-approval was the deciding factor two of the other offers had pre-qualifications only.
If you're even thinking about buying in the next six months, get pre-approved before you tour your first home. It costs nothing but a phone call and a few documents, and it puts you in the strongest possible position when the right house comes along. I can have your pre-approval ready in 24 to 48 hours once I have your file. This is not a commitment to lend.
Have questions about your mortgage?
Book a free 15-minute call with Peter no credit pull required.
Related Articles
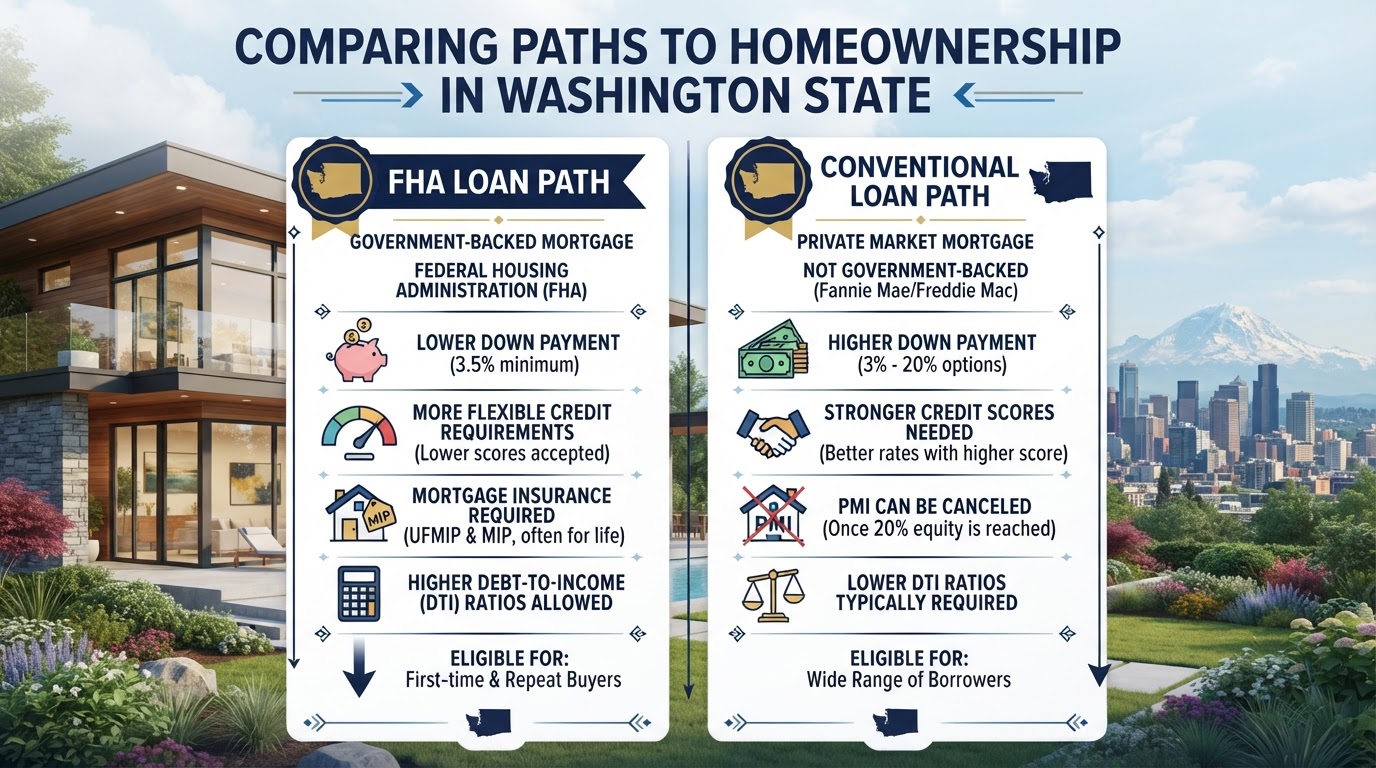
FHA vs Conventional Loans in Washington State: Which Is Right for You?
Comparing down payments, mortgage insurance, credit requirements, and costs to help Washington buyers choose between FHA and conventional financing.
7 First-Time Homebuyer Mistakes to Avoid in Washington State (And How to Dodge Them)
From underestimating closing costs to skipping the pre-approval, here are the most common first-time buyer mistakes in Washington and exactly how to avoid each one.
Condo vs. House in Washington: Which Is the Smarter First Purchase?
HOA fees, appreciation, maintenance, and lifestyle the real pros and cons of buying a condo versus a single-family home for Washington first-time buyers.