
A Manufactured Home on Owned Land in Pierce County: Yes, You Can Finance It
Reviewed by Peter Irungu, NMLS #2751063 | Last updated October 23, 2026
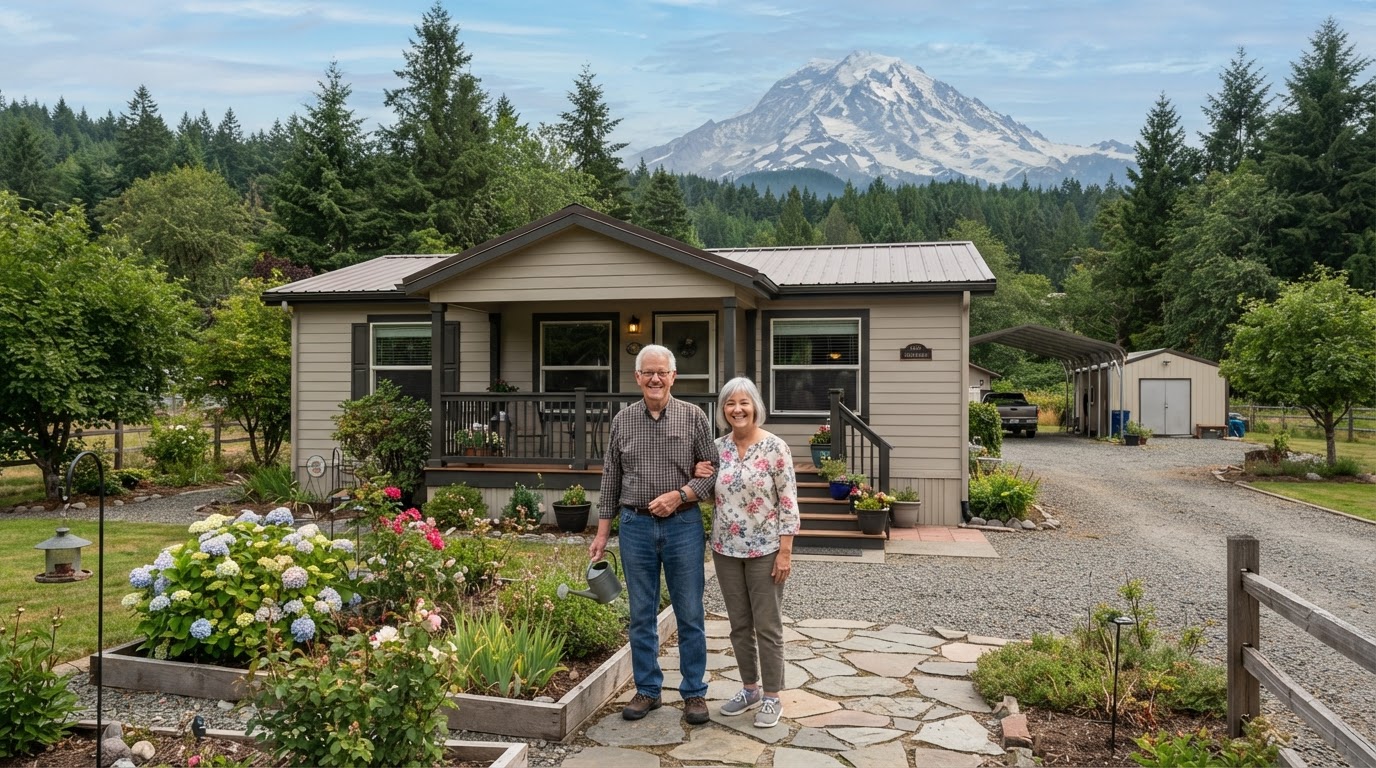
Linda and Bob, both in their early 60s, found the perfect retirement home: a newer manufactured home on a half-acre lot in Eatonville, listed at $245,000. It was affordable, single-level, and exactly what they wanted for their next chapter. But two lenders turned them down because it was a 'manufactured home.'
They called me frustrated and confused. Here's how we financed their manufactured home on owned land and why the right loan program made all the difference.
Manufactured vs. Mobile: What's the Difference?
First, the terminology matters. A 'manufactured home' is a factory-built home constructed after 1976 to federal HUD standards. A 'mobile home' is the older term for homes built before 1976. Modern manufactured homes are built to the same federal standards as site-built homes in many respects and can be financed with conventional, FHA, and specialized programs.
The key distinction for financing is whether the home is on owned land or in a park. Linda and Bob's home was on owned land they were buying both the home and the lot it sat on. This is called 'real property' financing, and it's very different from financing a manufactured home in a park (which is often treated as personal property, like a vehicle loan).
When a manufactured home is on owned land and properly affixed to a permanent foundation, it can be financed with FHA, conventional, or specialized manufactured home loan programs just like a site-built home.
Why Two Lenders Said No
The first two lenders Linda and Bob approached didn't offer manufactured home financing at all. Many big banks and credit unions don't have programs for manufactured homes not because they're bad investments, but because the specialized underwriting requirements are outside their standard product menu.
The issue wasn't Linda and Bob's credit (both scores above 720) or their income (solid retirement income plus Social Security). The issue was the property type. Some lenders simply don't lend on manufactured homes, period.
This is where working with a broker who has access to multiple lenders matters. I had access to several programs that finance manufactured homes on owned land, including FHA and specialized portfolio programs.
The FHA Manufactured Home Program
FHA insures loans for manufactured homes on owned land through its Title II program. The home must be built after 1976, meet HUD foundation requirements, and be classified as real property. Linda and Bob's home was built in 2019 and met all the requirements.
Their FHA loan required 3.5% down about $8,575 on a $245,000 purchase. Their closing costs were about $7,000, partially offset by a seller credit of $3,000. Their total out-of-pocket was about $12,500 well within their budget.
Their monthly payment including principal, interest, property taxes, and insurance was about $1,680 less than they'd been paying in rent for a smaller apartment in Puyallup. And they were building equity in a home they owned, on land they owned.
What to Know About Manufactured Home Financing
Manufactured home financing has some specific requirements: the home must be on a permanent foundation, classified as real property (not personal property), built after 1976, and in good condition. Some lenders have minimum square footage or age requirements.
The good news: if the home meets these requirements, the financing process is similar to a site-built home. FHA, conventional, and specialized programs are all available, and rates are competitive.
If you're considering a manufactured home on owned land in Pierce County or anywhere in Washington, don't assume you can't get financing. Let's look at your situation and find the right program for you.
All loan products, interest rates, and terms are subject to credit approval and market conditions. This is not a commitment to lend. Manufactured home financing requirements vary by lender and program. Programs, rates, terms, and conditions are subject to change without notice.
Have questions about your mortgage?
Book a free 15-minute call with Peter no credit pull required.
Related Articles
Washington State Down Payment Assistance Programs: Complete 2025 Guide
A guide to grants, forgivable loans, and second mortgages available to Washington homebuyers including Pierce County programs that may never require repayment.
Puyallup Home Prices and What Buyers Can Afford in Today's Market
A look at Puyallup and Pierce County home prices, what they mean for your monthly payment, and how to figure out what you can comfortably afford.
What Actually Happens on Closing Day? A Washington Homebuyer's Walkthrough
From the final walkthrough to the wire transfer to the keys in your hand here's exactly what to expect on closing day in Washington State, with no surprises.