
How Much Down Payment Do You Really Need in Washington? (It's Less Than You Think)
Reviewed by Peter Irungu, NMLS #2751063 | Last updated October 23, 2026
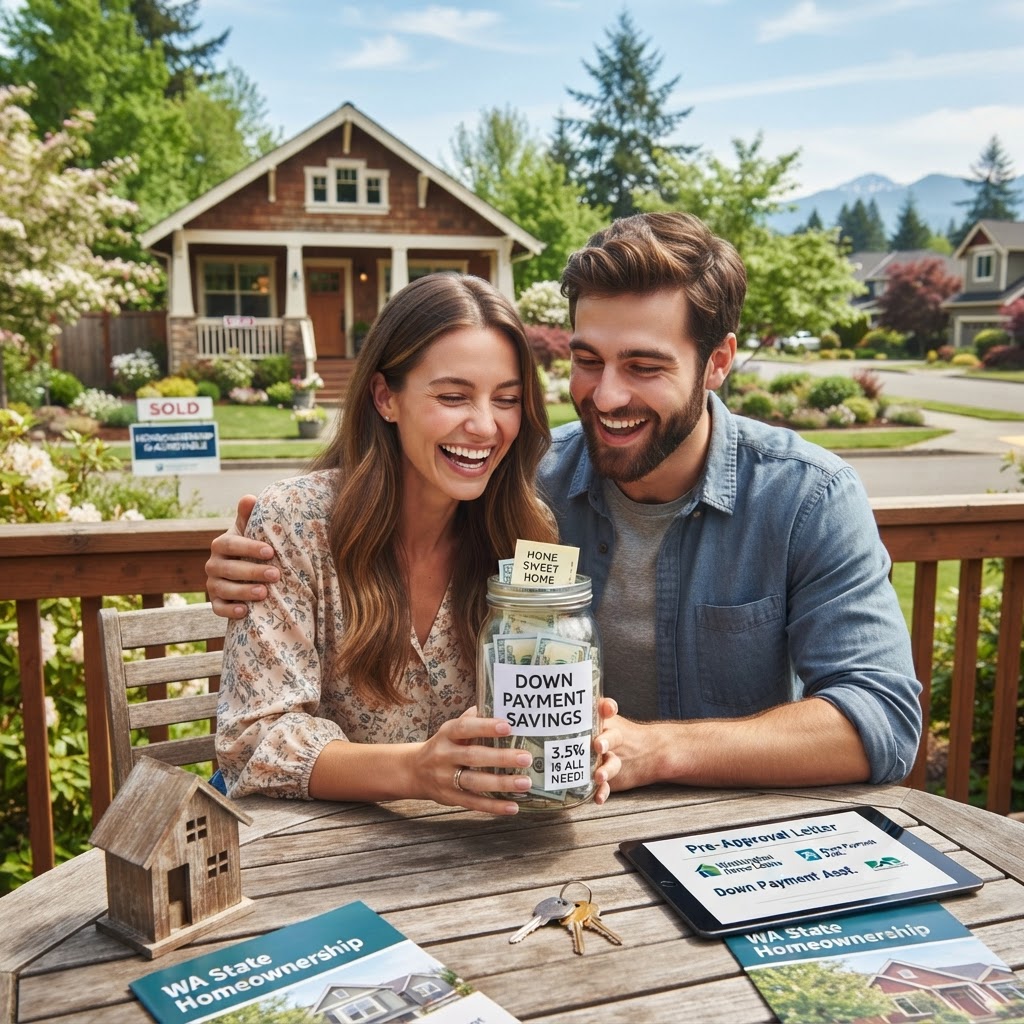
If you think you need 20% down to buy a home in Washington, you're not alone and you're probably wrong. The 20% down payment myth keeps more people on the sidelines than any other misconception in mortgage lending.
Let me clear this up: you can buy a home in Washington State with as little as 3% down on a conventional loan, 3.5% down on an FHA loan, or zero down with a VA loan. Here's how each one works.
FHA Loans: 3.5% Down
FHA loans require just 3.5% down for borrowers with credit scores of 580 or higher. On a $450,000 home in Puyallup, that's $15,750 not the $90,000 a 20% down payment would require.
The trade-off is mortgage insurance: an upfront premium plus monthly premiums that add to your payment. But for buyers who need a lower barrier to entry, FHA is often the path that makes homeownership possible.
Conventional Loans: As Low as 3% Down
Certain conventional loan programs allow 3% down for first-time and low-to-moderate income buyers. With a 620+ credit score, you may qualify for HomeReady or Home Possible programs that also offer reduced mortgage insurance costs.
The advantage over FHA: private mortgage insurance on a conventional loan can be cancelled once you reach 20% equity, while FHA mortgage insurance typically stays for the life of the loan.
VA Loans: Zero Down
If you've served in the military, a VA loan lets you buy with no down payment and no monthly mortgage insurance. It's the most powerful homebuying benefit available, and many eligible veterans in Pierce County never use it.
There's a one-time funding fee, but it can be financed into the loan and is waived for eligible disabled veterans. If you have a Certificate of Eligibility, let's talk.
Down Payment Assistance Can Close the Gap
Even 3% down can feel out of reach for some buyers. Washington State offers down payment assistance programs that provide grants or low-interest second mortgages to cover your down payment and closing costs.
Some programs never require repayment. I'll check which programs you may qualify for and help you stack them with your loan to minimize your out-of-pocket cost.
Have questions about your mortgage?
Book a free 15-minute call with Peter no credit pull required.
Related Articles
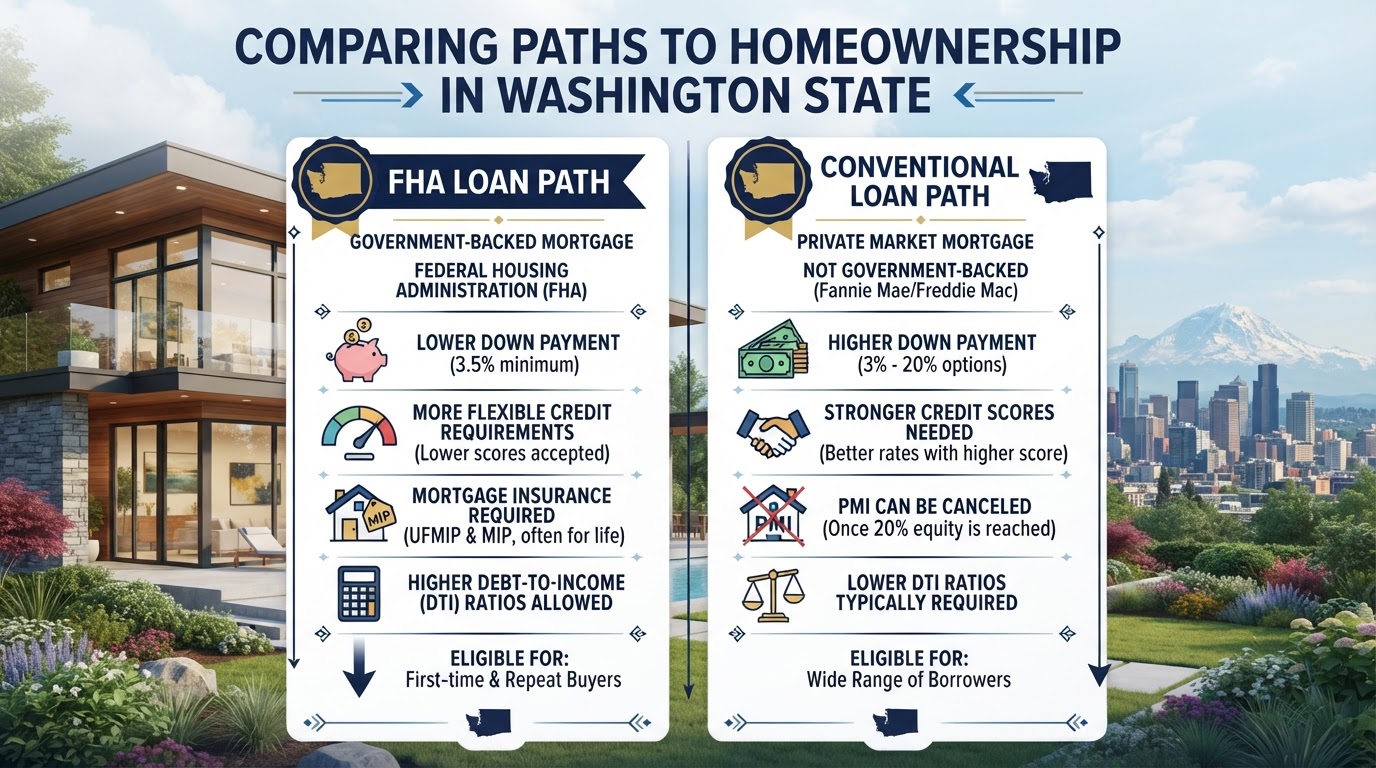
FHA vs Conventional Loans in Washington State: Which Is Right for You?
Comparing down payments, mortgage insurance, credit requirements, and costs to help Washington buyers choose between FHA and conventional financing.
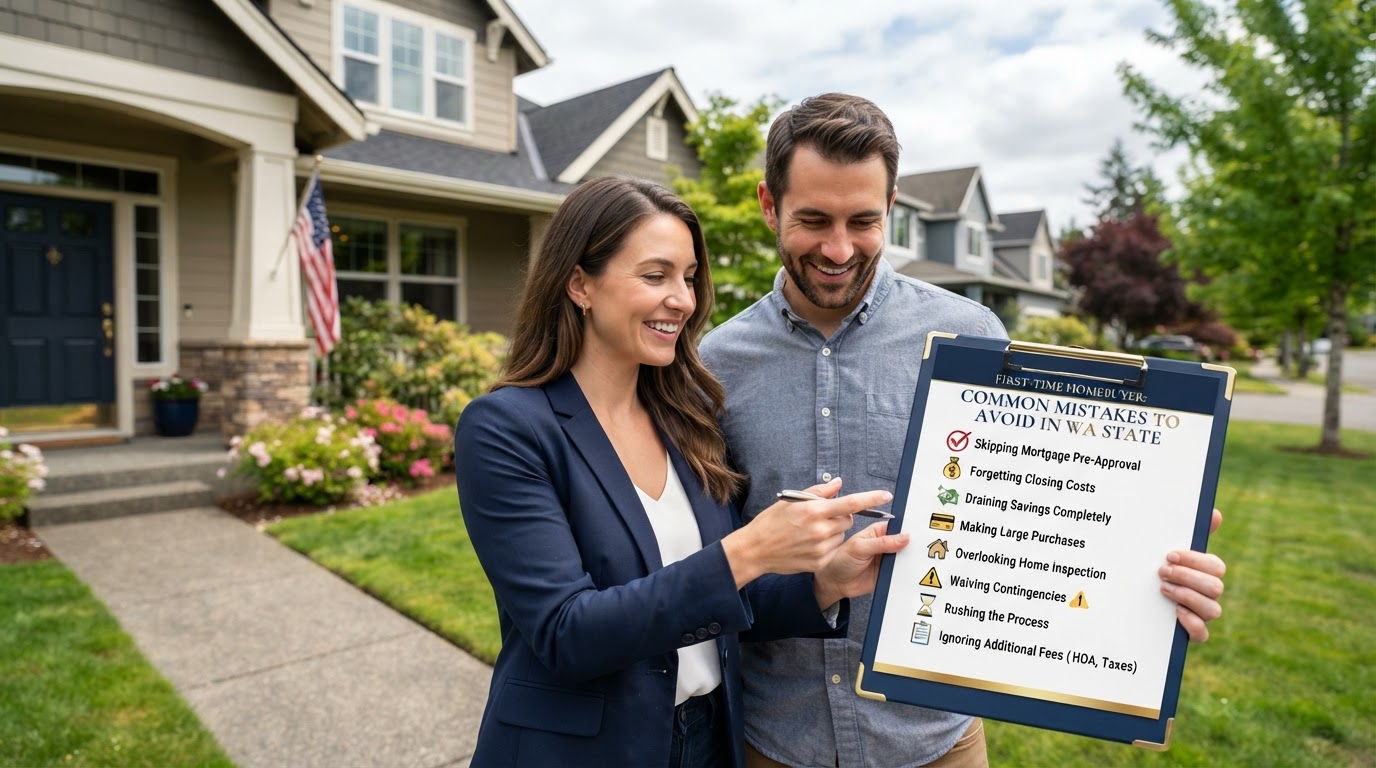
7 First-Time Homebuyer Mistakes to Avoid in Washington State (And How to Dodge Them)
From underestimating closing costs to skipping the pre-approval, here are the most common first-time buyer mistakes in Washington and exactly how to avoid each one.
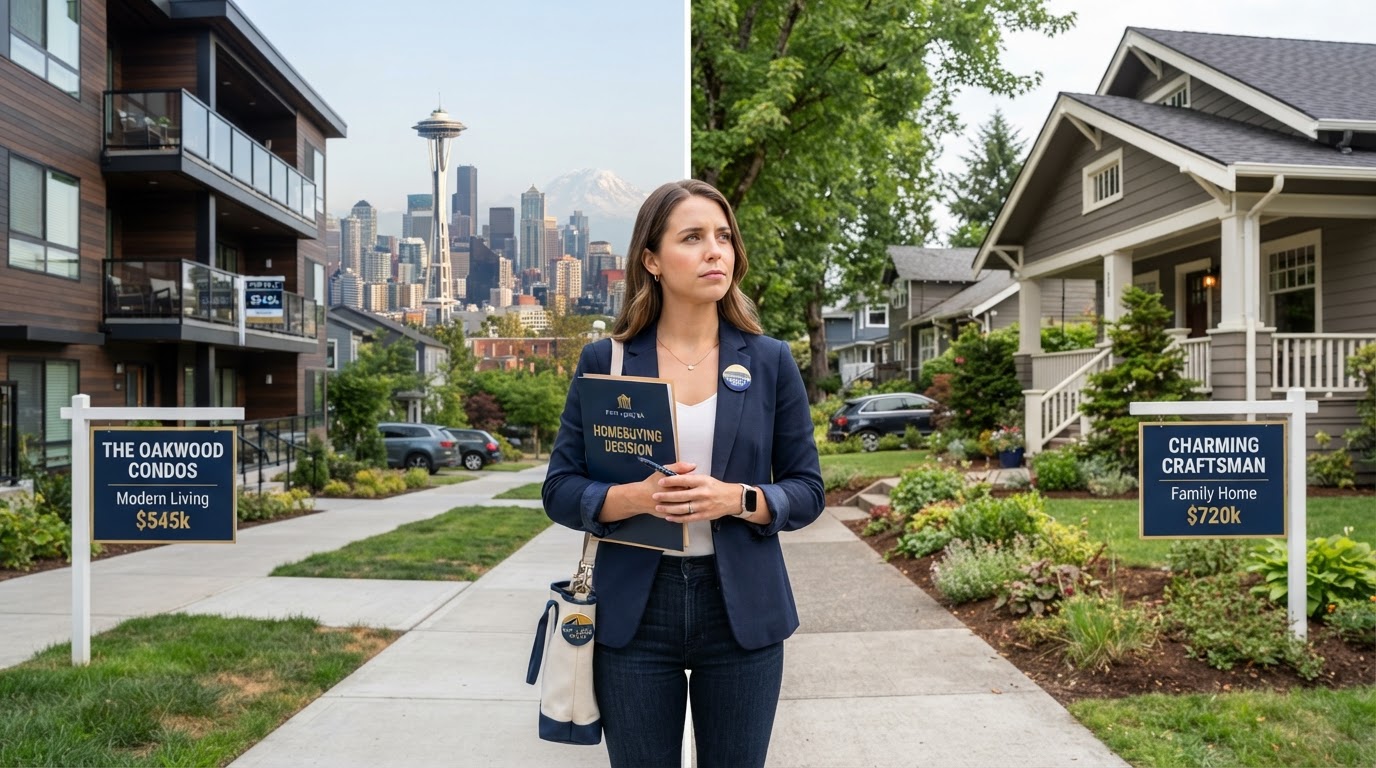
Condo vs. House in Washington: Which Is the Smarter First Purchase?
HOA fees, appreciation, maintenance, and lifestyle the real pros and cons of buying a condo versus a single-family home for Washington first-time buyers.