
From Renter to Homeowner in Puyallup: One Family's Journey from 'Someday' to Keys
Reviewed by Peter Irungu, NMLS #2751063 | Last updated October 23, 2026
Maria and David had been renting the same two-bedroom apartment in Puyallup for six years. Every month, they watched $1,850 disappear into someone else's mortgage. They'd talked about buying a home for years always with the same refrain: 'someday, when we have enough saved.'
Then their landlord raised the rent again, and 'someday' suddenly felt urgent. They called me on a Tuesday afternoon, both nervous and excited, with one question: 'Is it even possible for us?'
The answer was yes but the path there looked different than they expected. Here's how it went, step by step, so you can see what the journey from renter to homeowner actually looks like in Puyallup.
Step 1: The Conversation That Changed Everything
When Maria and David came in, they assumed they needed $80,000 saved for a down payment the 20% they'd always heard about. I showed them their actual options: an FHA loan with 3.5% down, a conventional loan with as little as 3% down, and a Washington down payment assistance program that could cover part of their closing costs.
On a $425,000 home in Puyallup, 3.5% down is about $14,875 not $85,000. That single conversation reframed what was possible. They left my office that day not with a loan, but with a plan and a number to aim for.
That's what the first conversation should do. Not sell you a loan. Give you a map.
Step 2: The Credit Score Surprise
David's credit score was 672 solid, but not where he thought it should be. Maria's was 645. They'd both been afraid their scores were too low to qualify. In reality, both scores were above the 620 conventional minimum and well above the 580 FHA threshold.
What they didn't know was that David had a small medical collection from 2022 that was dragging his score down. We didn't need to pay it off to qualify but I showed him that disputing an outdated address on the account could clean up the reporting. Two weeks later, his score jumped 28 points.
Sometimes the fastest path to a better rate isn't a bigger down payment. It's a 20-minute credit review.
Step 3: The Down Payment Assistance Discovery
Here's where the story takes a turn neither of them expected. Maria and David had never heard of Washington's down payment assistance programs. When I told them about the Home Advantage program which pairs a below-market first mortgage with a second loan that can cover down payment and closing costs they were skeptical. 'There's no way that's free,' David said.
It's not free, exactly. The assistance is a deferred second mortgage, meaning repayment is deferred until you sell, refinance, or pay off the first loan. But for a family trying to get into their first home, it can be the difference between waiting another year and buying now.
With the assistance program stacked onto their FHA loan, their out-of-pocket dropped from roughly $25,000 to about $9,500. That was money they already had in savings.
Step 4: The Offer That Almost Didn't Happen
They found a three-bedroom home near Meridian in Puyallup listed at $439,000, which was just above their pre-approval range. Their agent suggested offering $432,000 with a request for $5,000 in seller credits toward closing costs. The seller countered at $436,000 with $3,000 in credits.
Maria wanted to walk. David wanted to accept. They called me on a Saturday morning, and we ran the numbers together: at $436,000 with 3.5% down, their monthly payment including taxes and insurance was about $2,890 roughly $1,040 more than their rent, but building equity from day one instead of paying their landlord's mortgage.
They accepted the counter. The appraisal came in at $438,000. The inspection found a roof with about five years of life left not a dealbreaker, but we negotiated $2,000 in additional seller credits to address it.
Step 5: Closing Day
Thirty-four days after their offer was accepted, Maria and David sat at a closing table in Tacoma and signed the last of what felt like a hundred documents. Their total out-of-pocket: about $11,200 down payment assistance, seller credits, and their own savings combined.
Their monthly payment, including principal, interest, property taxes, and insurance: $2,890. Their first mortgage payment was due in about six weeks, giving them time to settle in.
I got a text from Maria that evening: 'We're sitting on our own porch. David is grilling. I can't stop crying.' That's the moment this job is really about.
What Their Story Means for You
Maria and David's journey wasn't extraordinary. They didn't have perfect credit, a huge down payment, or a flawless financial profile. What they had was a willingness to start the conversation and a loan officer who took the time to map out every option instead of just running their numbers and sending them a rate quote.
If you're renting in Puyallup, Tacoma, or anywhere in Pierce County and wondering whether buying is possible for you, the answer is probably 'yes, and here's how.' The first step is a 15-minute conversation. No credit pull required. Just a map.
All loan products, interest rates, and terms are subject to credit approval and market conditions. This is not a commitment to lend. Programs, rates, terms, and conditions are subject to change without notice.
Have questions about your mortgage?
Book a free 15-minute call with Peter no credit pull required.
Related Articles
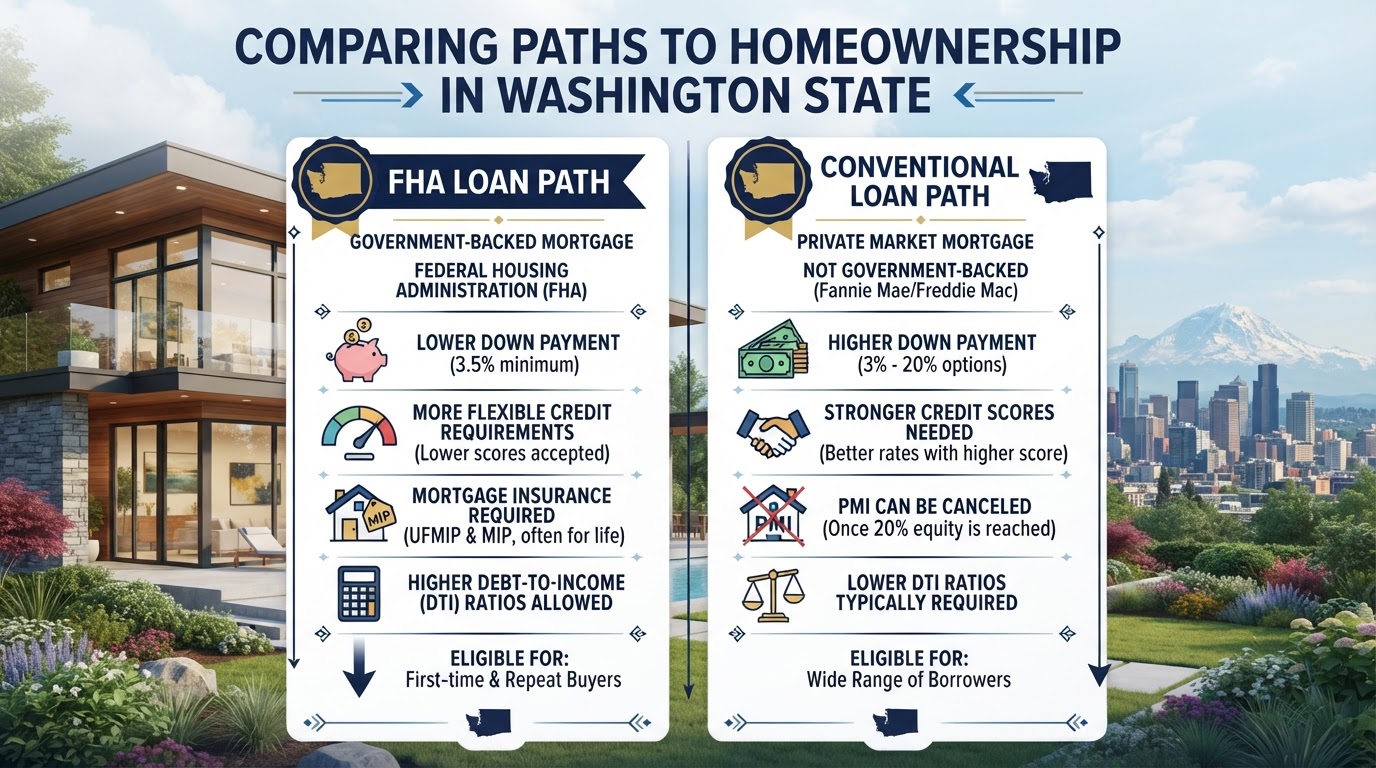
FHA vs Conventional Loans in Washington State: Which Is Right for You?
Comparing down payments, mortgage insurance, credit requirements, and costs to help Washington buyers choose between FHA and conventional financing.
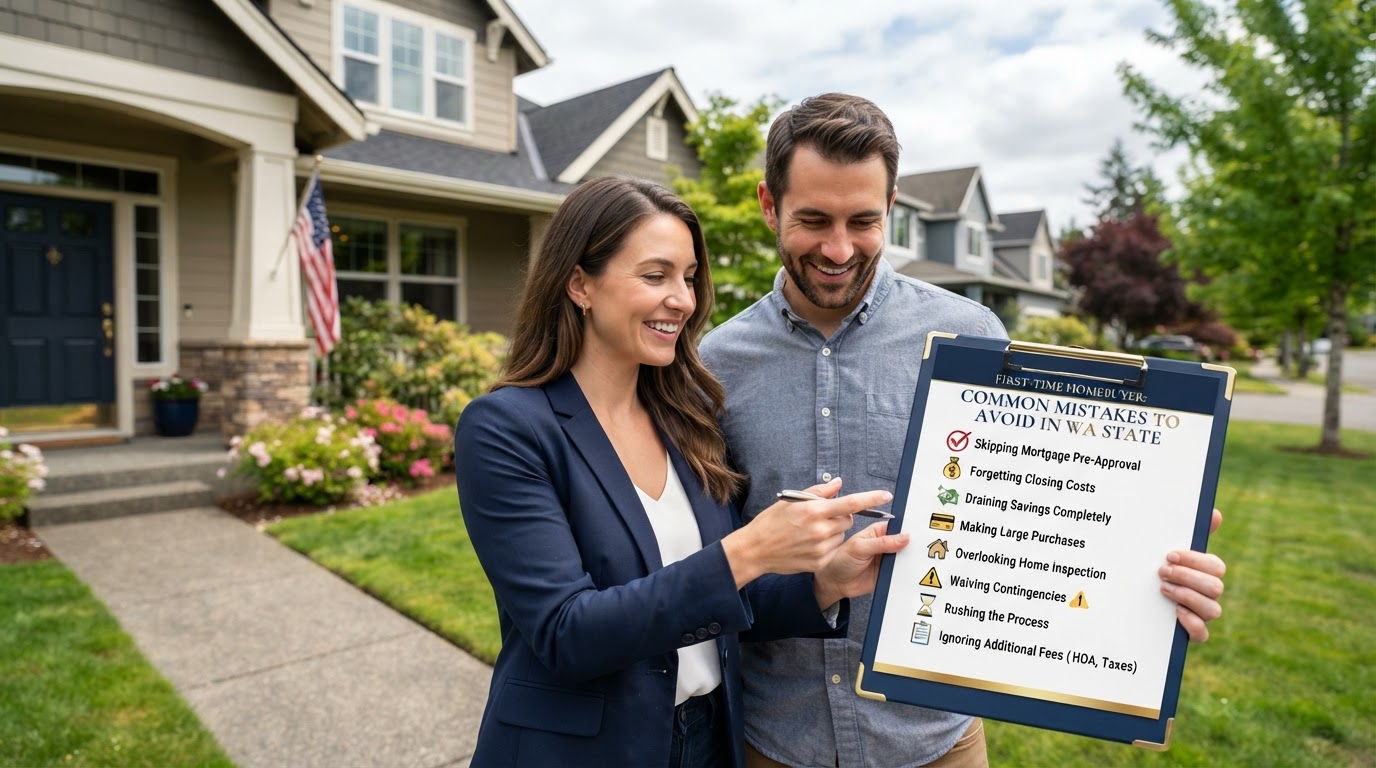
7 First-Time Homebuyer Mistakes to Avoid in Washington State (And How to Dodge Them)
From underestimating closing costs to skipping the pre-approval, here are the most common first-time buyer mistakes in Washington and exactly how to avoid each one.
Condo vs. House in Washington: Which Is the Smarter First Purchase?
HOA fees, appreciation, maintenance, and lifestyle the real pros and cons of buying a condo versus a single-family home for Washington first-time buyers.