
How a Seattle Teacher Bought Her First Home in Kent with 3% Down and Down Payment Assistance
Reviewed by Peter Irungu, NMLS #2751063 | Last updated October 23, 2026
Jessica was a 31-year-old special education teacher in the Kent School District. She made $72,000 a year, had a 705 credit score, and had saved $14,000. In King County, that felt like nowhere near enough until she learned about HomeReady and Washington's down payment assistance programs.
Here's how Jessica bought a $415,000 condo in Kent with 3% down and how down payment assistance covered most of her closing costs.
The 3% Down Conventional Option
Jessica qualified for Fannie Mae's HomeReady program a conventional loan that allows 3% down for first-time and low-to-moderate income buyers. On a $415,000 condo, 3% down is $12,450. That's dramatically less than the 20% ($83,000) most people assume they need.
HomeReady also offers reduced mortgage insurance costs compared to standard conventional loans, which lowered Jessica's monthly payment. And unlike FHA, the mortgage insurance on a HomeReady loan can be cancelled once she reaches 20% equity it doesn't stay for the life of the loan.
Jessica's income of $72,000 was under the HomeReady income limit for King County, which made her eligible. The program is designed for buyers in designated low-to-moderate income areas, and many parts of Kent, Auburn, and Federal Way qualify.
Stacking Down Payment Assistance
Here's where it got powerful. Jessica's $14,000 in savings covered her $12,450 down payment but she still needed about $8,000 for closing costs. That's where Washington's Home Advantage down payment assistance came in.
The Home Advantage DPA program provided a second mortgage of about $12,000 (3% of her first loan amount) that covered her closing costs and left her with a small reserve. The DPA loan is deferred meaning she doesn't make payments on it, and it's repaid when she sells, refinances, or pays off the first mortgage.
So Jessica's total out-of-pocket at closing was about $1,200 the difference between her savings and the combined down payment plus DPA. She walked into her first home with her savings intact and a monthly payment she could comfortably afford.
The Income Limits and Homebuyer Education
Home Advantage has income limits that vary by household size and area. For Jessica as a single borrower in King County, the limit was well above her $72,000 income. But if she'd had a partner or other income earners in the household, the combined income would have been measured against the limit.
Jessica also completed a free homebuyer education course a requirement for the DPA program. The course covered budgeting, the mortgage process, and what to expect as a homeowner. She told me it was genuinely helpful, not just a checkbox.
The homebuyer education requirement is common across Washington's assistance programs. It ensures buyers understand the responsibility they're taking on and it's free through the Washington State Housing Finance Commission.
What Jessica's Numbers Looked Like
Jessica's first mortgage: $402,550 (after 3% down). Her rate was competitive lower than FHA would have been for her credit profile. Her monthly payment including principal, interest, property taxes, insurance, and HOA was about $2,890.
Her DPA second mortgage: about $12,000, deferred, no monthly payment. When she sells or refinances, she'll pay it back but until then, it costs her nothing monthly.
Jessica's total out-of-pocket at closing: about $1,200. She moved into her first home with $12,800 still in savings a safety net that made the whole process feel less scary.
If you're a first-time buyer in King County wondering whether you can afford to buy, the answer might surprise you. Let's run the numbers for your situation and see what programs you qualify for.
All loan products, interest rates, and terms are subject to credit approval and market conditions. This is not a commitment to lend. Down payment assistance programs have income and eligibility requirements. Programs, rates, terms, and conditions are subject to change without notice.
Have questions about your mortgage?
Book a free 15-minute call with Peter no credit pull required.
Related Articles
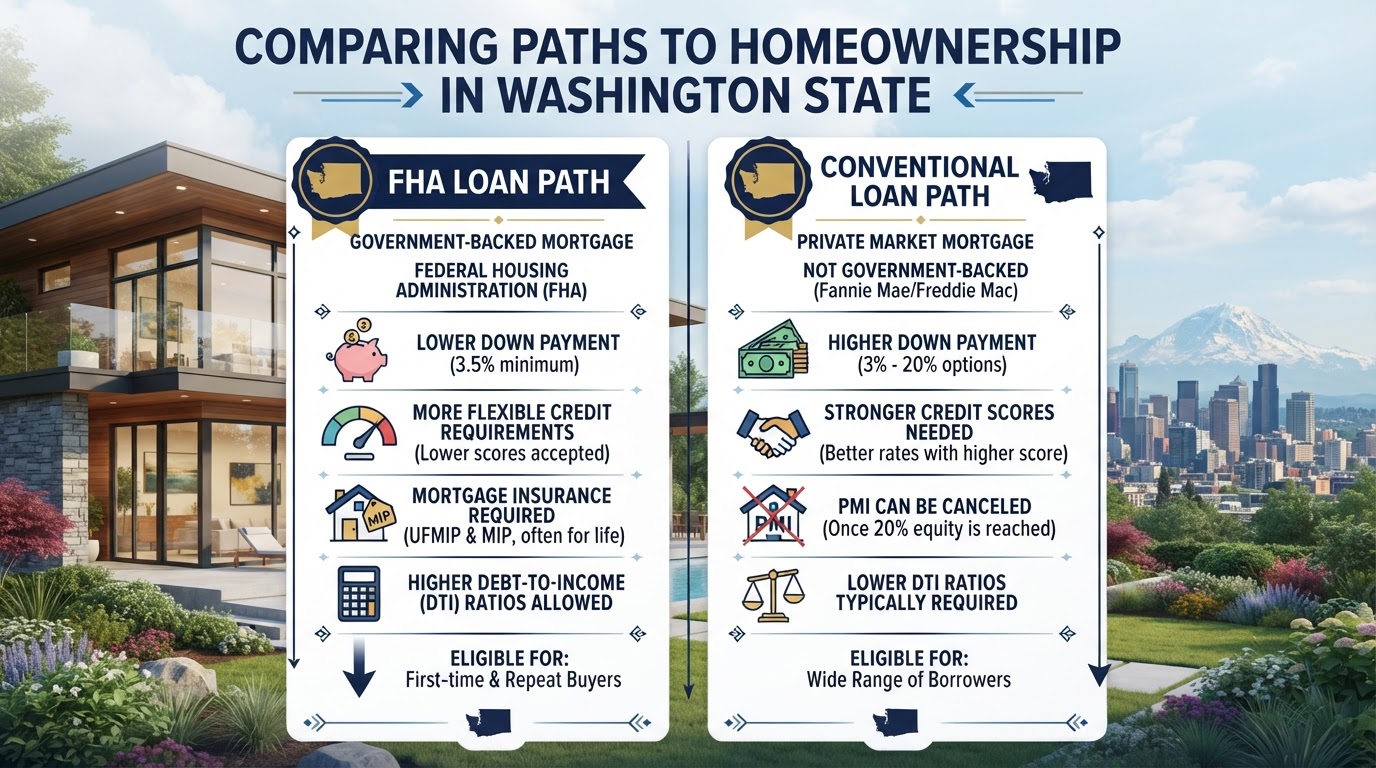
FHA vs Conventional Loans in Washington State: Which Is Right for You?
Comparing down payments, mortgage insurance, credit requirements, and costs to help Washington buyers choose between FHA and conventional financing.
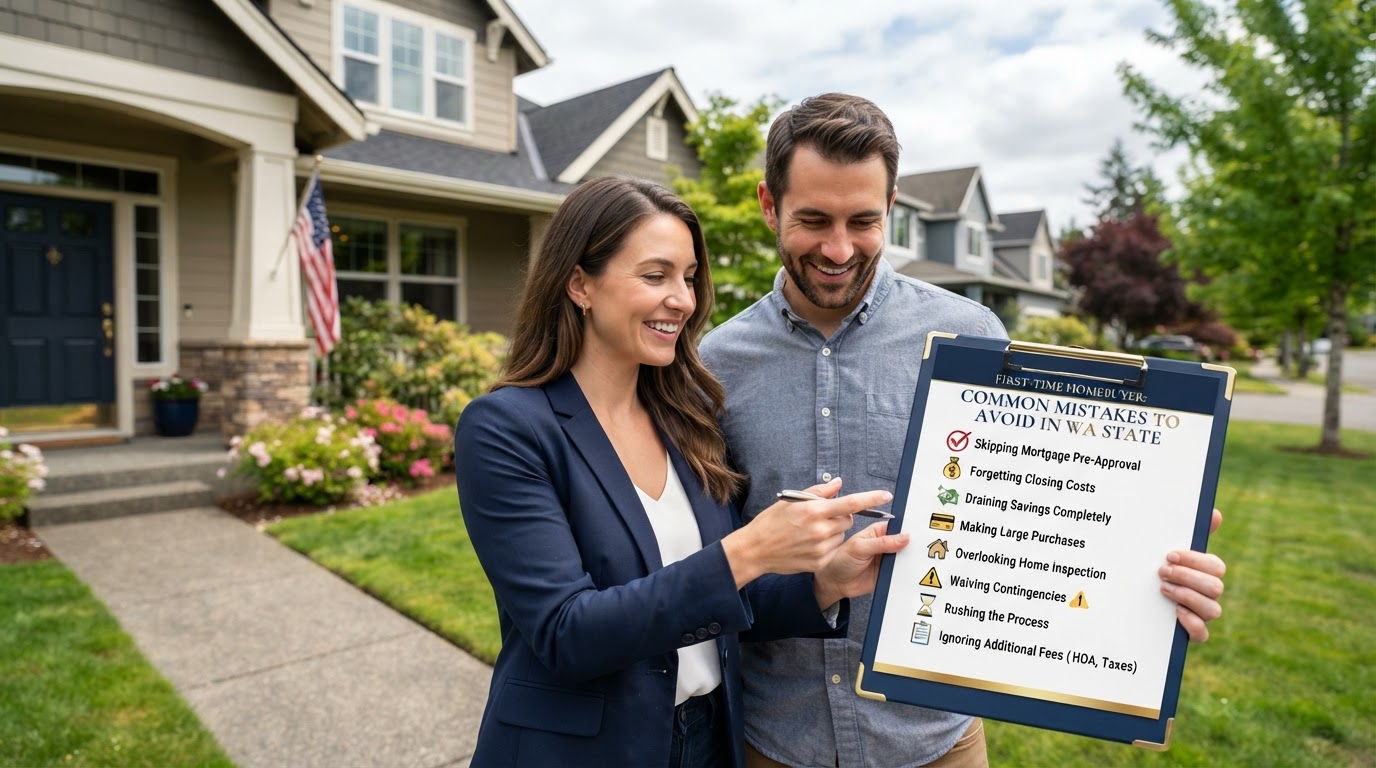
7 First-Time Homebuyer Mistakes to Avoid in Washington State (And How to Dodge Them)
From underestimating closing costs to skipping the pre-approval, here are the most common first-time buyer mistakes in Washington and exactly how to avoid each one.
Condo vs. House in Washington: Which Is the Smarter First Purchase?
HOA fees, appreciation, maintenance, and lifestyle the real pros and cons of buying a condo versus a single-family home for Washington first-time buyers.