
The Ugly Duckling Home: How a First-Time Buyer Used an FHA 203(k) Loan to Turn a Fixer into a Dream Home
Reviewed by Peter Irungu, NMLS #2751063 | Last updated October 23, 2026
Tom and Lisa found their dream home or rather, their dream home's bones. The house was a 1960s ranch in Puyallup with good bones, a great lot, and a price tag of $365,000 that reflected its condition: dated kitchen, original bathrooms, single-pane windows, and a roof with maybe five years left.
A conventional buyer would have walked away. Tom and Lisa didn't have $80,000 in cash for renovations after a down payment. But they didn't need to because an FHA 203(k) renovation loan let them finance the purchase and the renovations in a single loan. Here's how it worked.
What an FHA 203(k) Loan Actually Does
An FHA 203(k) loan is a renovation mortgage that lets you buy a home and finance the cost of repairs, upgrades, or renovations into a single loan. You close once, with one down payment and one monthly payment, and the renovation funds are held in escrow and released as the work is completed and inspected.
There are two types: the Standard 203(k) for major renovations (structural changes, room additions, plumbing and electrical overhauls) and the Limited 203(k) for smaller projects (up to about $35,000 in renovations, no structural work). Tom and Lisa needed the Standard version because their project included a kitchen gut, two bathroom redos, and a roof replacement.
The key advantage: you're buying and renovating with one loan, one closing, and one set of qualifications. You don't need a separate construction loan, a second mortgage, or cash for renovations. The home's after-improvement value is what supports the loan.
The Numbers Behind Tom and Lisa's Project
Purchase price: $365,000. Renovation budget: $72,000 (kitchen, two bathrooms, roof, windows, flooring, paint). Total loan amount: about $445,000 (purchase plus renovations, minus 3.5% down on the total).
Their down payment (3.5% of the total project cost): about $15,575. Their closing costs: about $11,000, partially offset by $4,000 in seller credits. Total out-of-pocket: about $22,500.
After renovations, the home appraised at $485,000 meaning Tom and Lisa had about $40,000 in equity from day one. Their monthly payment including principal, interest, property taxes, insurance, and FHA mortgage insurance: about $3,380. Not cheap, but they were in a fully renovated home worth more than they paid including the renovation costs.
How the Renovation Process Worked
The 203(k) process requires a licensed contractor you can't do the work yourself on a Standard 203(k). Tom and Lisa got three bids, chose a contractor, and submitted the bids with their loan application. The lender approved the renovation budget and set up a draw schedule.
As each phase of work was completed demolition, rough-in, finishes the contractor submitted the work for inspection. Once the inspector confirmed the work was done correctly, the lender released the next draw from the escrow account. Tom and Lisa never handled the renovation money directly; the lender managed the disbursements.
The renovation took four months. Tom and Lisa lived in the home during construction not ideal, but manageable because they'd planned for it. When the final inspection passed, the last draw was released, and their home was complete.
Who an FHA 203(k) Is Right For
A 203(k) loan is ideal for buyers who find a home in a great location at a great price but who can't afford the renovations out of pocket. It's also useful for buyers who want to customize a home to their taste rather than paying a premium for someone else's renovations.
The trade-offs: the process is more complex than a standard purchase, the renovation timeline adds stress, and you need a contractor who understands 203(k) requirements. But for the right buyer and the right property, it's one of the best tools in the FHA toolkit.
If you've found a fixer-upper in Pierce County or King County and you're wondering how to finance the renovations, let's talk. I'll walk you through the 203(k) process, help you understand the numbers, and connect you with contractors who know the program.
NEXA Lending, LLC is a private mortgage company and is not affiliated with, endorsed by, or acting on behalf of HUD, FHA, or any government agency. FHA 203(k) loans require an approved contractor and HUD-approved consultant for Standard 203(k) projects. This is not a commitment to lend. All loan products, rates, and terms are subject to credit approval and market conditions.
Have questions about your mortgage?
Book a free 15-minute call with Peter no credit pull required.
Related Articles
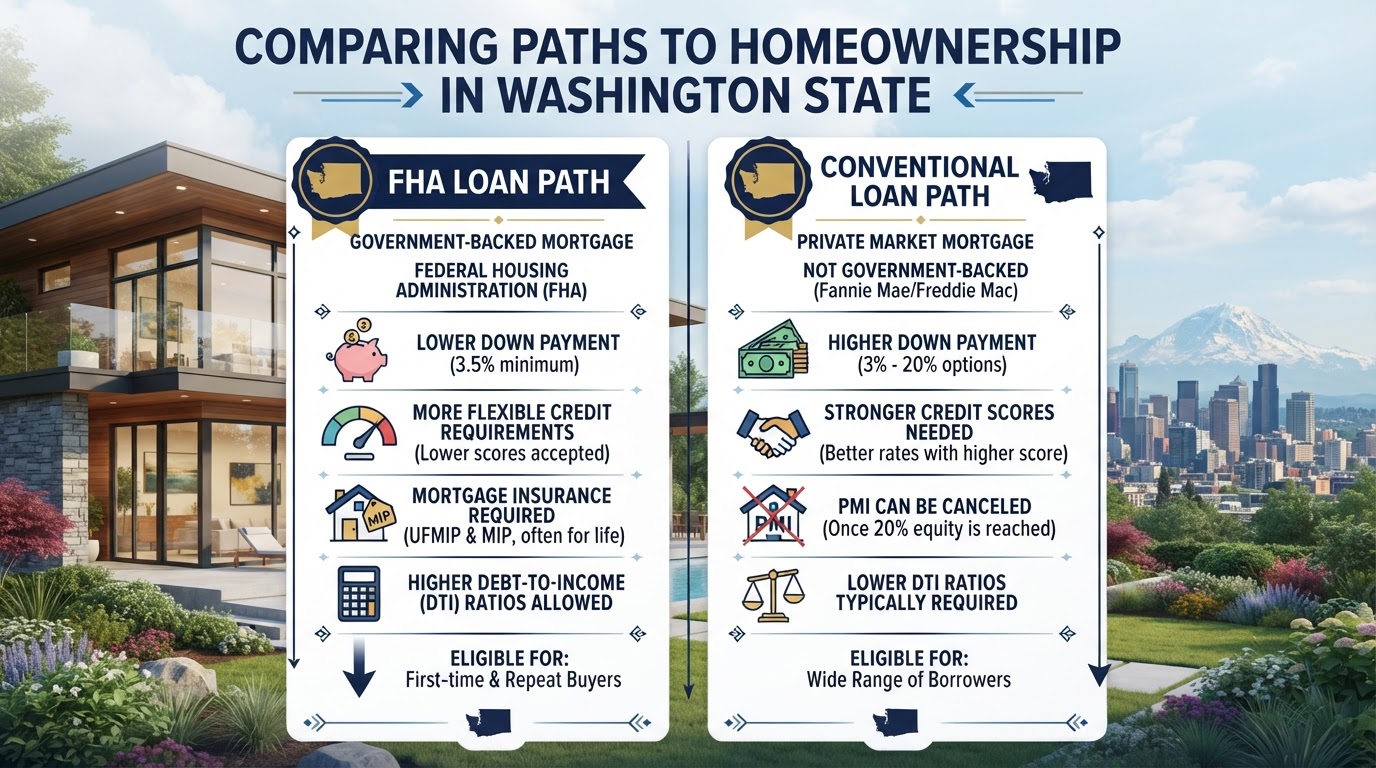
FHA vs Conventional Loans in Washington State: Which Is Right for You?
Comparing down payments, mortgage insurance, credit requirements, and costs to help Washington buyers choose between FHA and conventional financing.
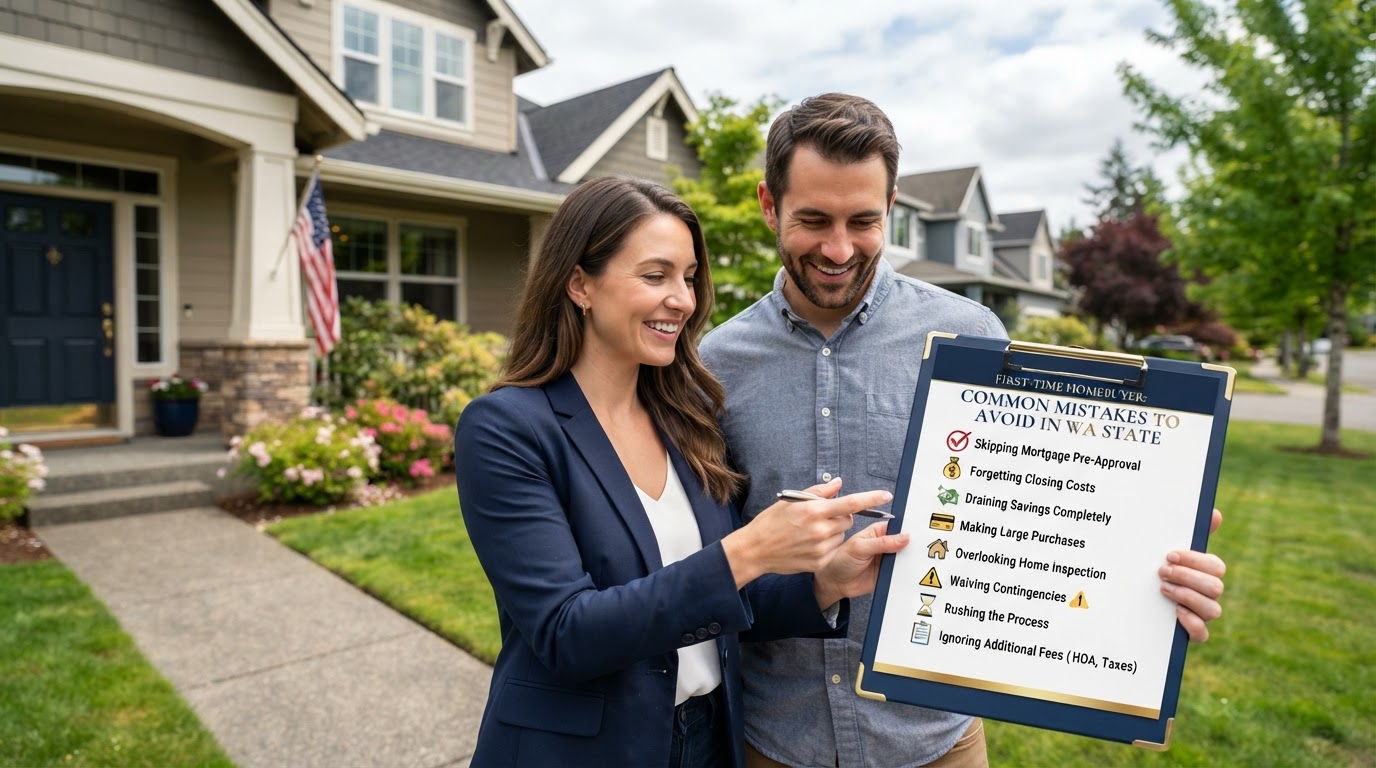
7 First-Time Homebuyer Mistakes to Avoid in Washington State (And How to Dodge Them)
From underestimating closing costs to skipping the pre-approval, here are the most common first-time buyer mistakes in Washington and exactly how to avoid each one.
Condo vs. House in Washington: Which Is the Smarter First Purchase?
HOA fees, appreciation, maintenance, and lifestyle the real pros and cons of buying a condo versus a single-family home for Washington first-time buyers.