
Condo or House? How a First-Time Buyer in Auburn Weighed the Trade-Offs and Chose Right
Reviewed by Peter Irungu, NMLS #2751063 | Last updated October 23, 2026
Amanda was 29 and buying her first home in Auburn. She had $22,000 saved and a pre-approval for $380,000. The question wasn't whether she could buy it was what she should buy: a condo in a newer building near downtown Auburn, or a small single-family home further out.
The condo was $345,000 with low maintenance, a garage, and walkable to the train station. The house was $375,000 with a yard, more space, and a longer commute. Both were within her budget. Both made sense for different reasons. Here's how she decided and the loan considerations that shaped her choice.
The Financial Comparison
The condo had a lower purchase price ($345,000 vs $375,000) and lower property taxes, but it came with HOA dues of $285 per month. The house cost more upfront and had higher property taxes, but no HOA and the maintenance was her responsibility.
On a monthly basis, the condo's payment including HOA was about $2,680. The house's payment including taxes and insurance was about $2,890. The difference was $210 per month but the house came with a yard, privacy, and no shared walls.
Amanda also had to consider maintenance. The condo's HOA covered exterior maintenance, landscaping, and some utilities. The house meant she was responsible for everything the roof, the water heater, the lawn. She budgeted $200 per month for maintenance on the house, which brought the real monthly cost closer to parity.
The Loan Considerations
Both properties qualified for FHA and conventional financing, but the condo had an extra wrinkle: FHA requires the condo complex to be on an approved list. Not all complexes are approved, and if the one Amanda was considering wasn't, she'd need a conventional loan instead which required a slightly higher down payment.
Fortunately, the complex was FHA-approved, so Amanda could use her FHA loan with 3.5% down on either property. On the condo, 3.5% down was about $12,075. On the house, it was about $13,125. Both were within her $22,000 savings plus closing cost assistance.
If you're considering a condo, ask me to check FHA approval status early in your search. It can affect your loan options and your down payment requirements.
The Lifestyle Decision
Amanda chose the house. Not because it was the better financial decision on paper, the condo was slightly cheaper when you factored in HOA. She chose the house because she wanted a yard for her dog, a garden she'd been dreaming about, and the freedom to paint, renovate, and customize without asking an HOA board.
The condo would have been the right choice for a different buyer someone who valued low maintenance, walkability, and predictable costs over space and autonomy. There's no wrong answer. The right answer depends on your lifestyle, your priorities, and your five-year plan.
Amanda's house needed work the kitchen was dated and the bathroom needed updating within a few years. She used a conventional loan and planned to save for renovations over time. If she'd wanted to finance the renovations upfront, an FHA 203(k) would have been an option but she preferred to tackle projects as she could afford them.
How to Decide for Yourself
If you're weighing a condo versus a house, here are the questions to ask: How long do you plan to stay? (Longer horizons favor houses for equity building.) Do you want low maintenance or control? (Condos offer low maintenance; houses offer control.) What's your commute? (Condos near transit can save time and gas.) What's your tolerance for HOA rules? (Some people love the structure; others chafe under it.)
On the loan side, I'll help you compare the total monthly cost of each including HOA, taxes, insurance, and maintenance reserves so you're comparing the real cost, not just the mortgage payment. And I'll check FHA condo approval status so you know your financing options before you make an offer.
All loan products, interest rates, and terms are subject to credit approval and market conditions. This is not a commitment to lend. FHA condo approval requirements apply to condominium purchases. Programs, rates, terms, and conditions are subject to change without notice.
Have questions about your mortgage?
Book a free 15-minute call with Peter no credit pull required.
Related Articles
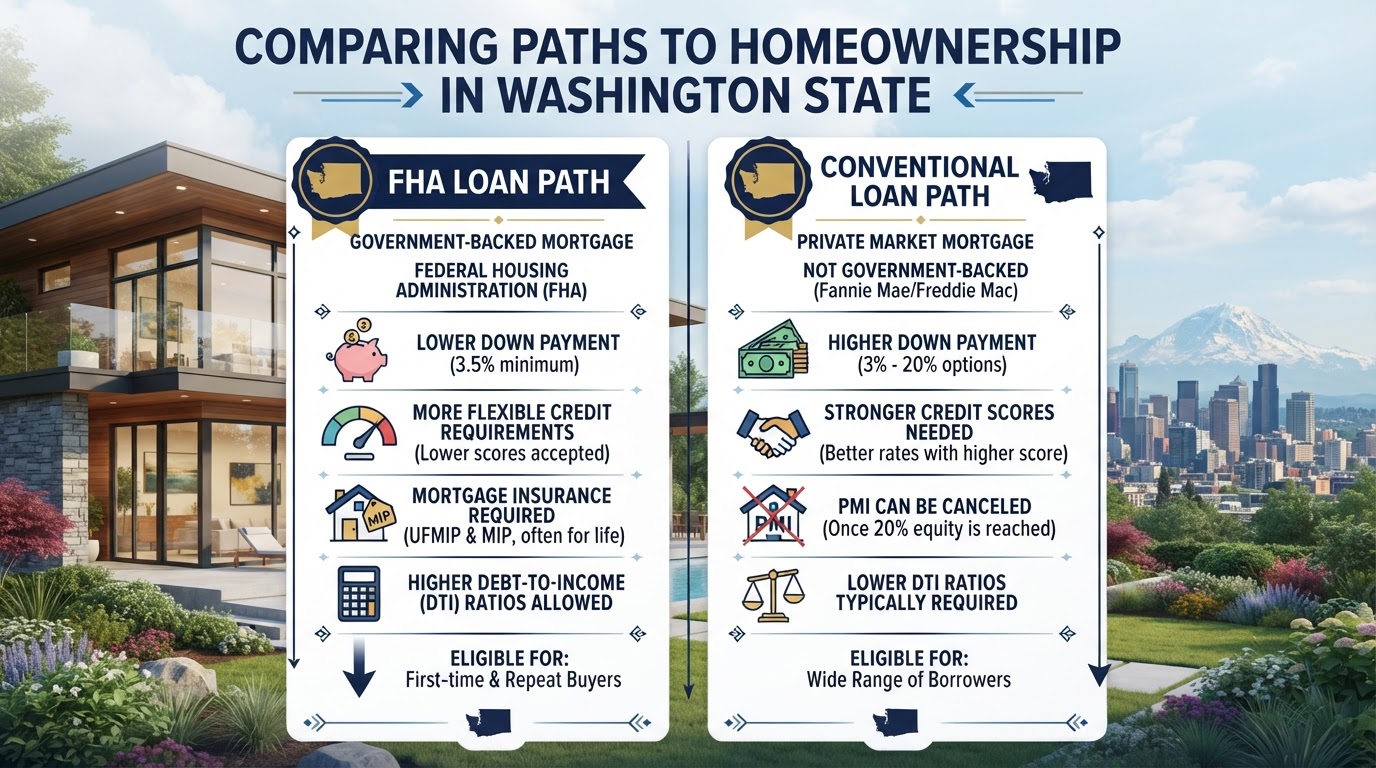
FHA vs Conventional Loans in Washington State: Which Is Right for You?
Comparing down payments, mortgage insurance, credit requirements, and costs to help Washington buyers choose between FHA and conventional financing.
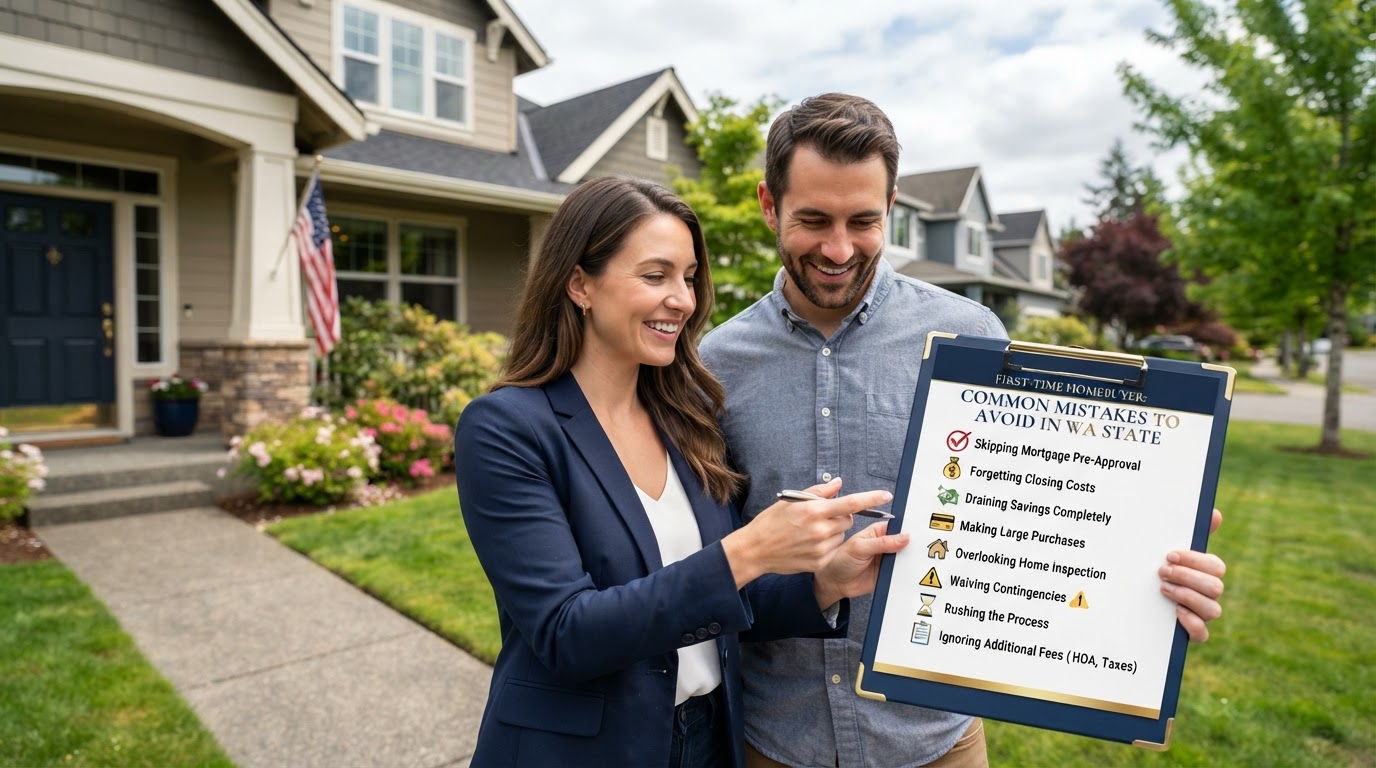
7 First-Time Homebuyer Mistakes to Avoid in Washington State (And How to Dodge Them)
From underestimating closing costs to skipping the pre-approval, here are the most common first-time buyer mistakes in Washington and exactly how to avoid each one.
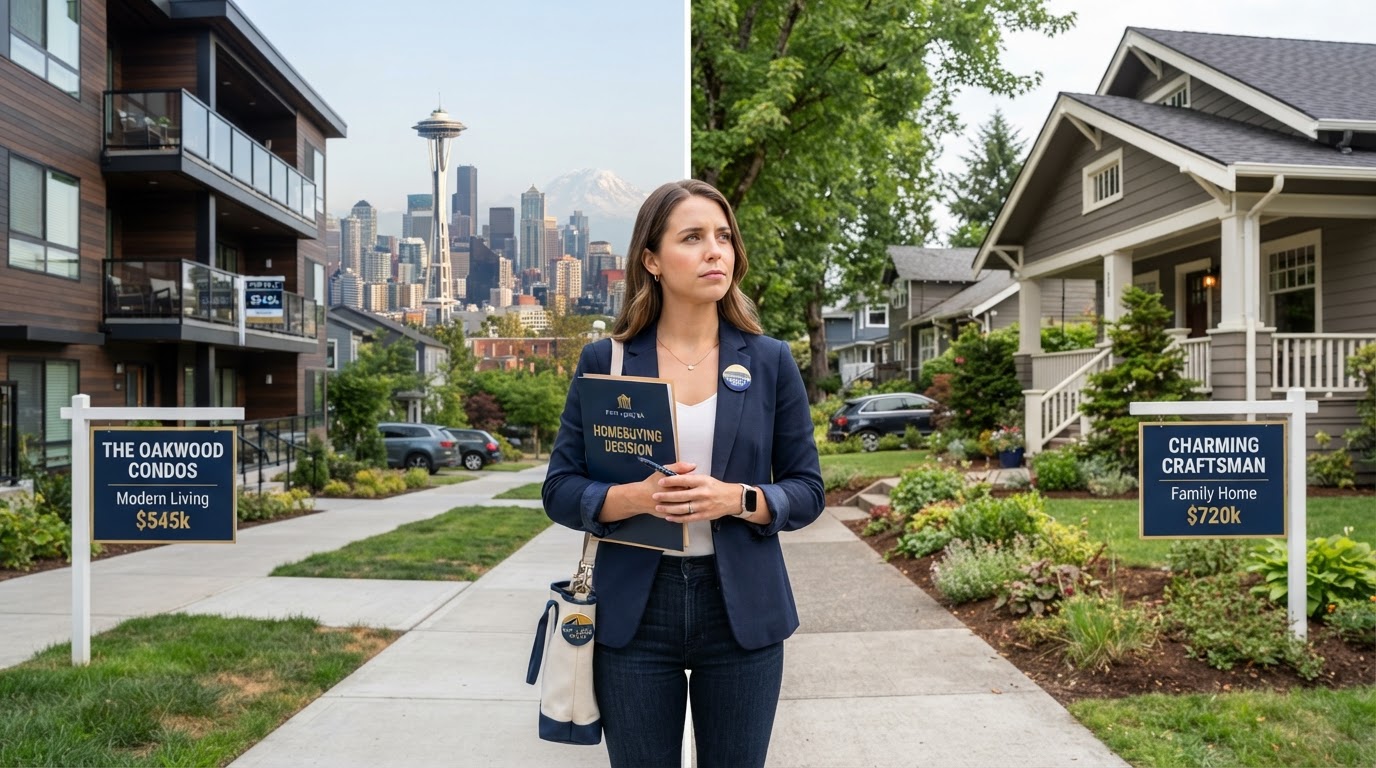
Condo vs. House in Washington: Which Is the Smarter First Purchase?
HOA fees, appreciation, maintenance, and lifestyle the real pros and cons of buying a condo versus a single-family home for Washington first-time buyers.