
When Your Parents Co-Sign: How a Spokane Family Helped Their Son Buy His First Home
Reviewed by Peter Irungu, NMLS #2751063 | Last updated October 23, 2026
Marcus was 25 and working as an electrician in Spokane. He made $62,000 a year solid for his age but he'd only been at his current employer for 14 months, and his credit score was 648. On paper, he qualified for a conventional loan, but barely. His debt-to-income ratio was tight, and the payment on a $350,000 home would push him over the 45% threshold most lenders prefer.
His parents, Robert and Diane, offered to co-sign. They'd done well owned their home free and clear, had strong credit, and wanted to help their son get into the market before prices climbed further. Here's how co-signing worked for Marcus's family, and what you should know before you consider it.
What Co-Signing Actually Means
A co-signer more accurately called a non-occupant co-borrower on a conventional loan is someone who applies for the mortgage alongside the primary borrower but doesn't live in the home. Their income, assets, and credit are considered alongside the primary borrower's, which can strengthen the application and improve the debt-to-income ratio.
Marcus's parents added their retirement income and investment income to the application. Combined with Marcus's wages, the household qualifying income rose enough that the debt-to-income ratio dropped from 46% to 34% comfortably within approval range. Their strong credit scores (both above 780) also helped the overall loan profile.
The key distinction: a co-signer is equally responsible for the loan. If Marcus misses a payment, it affects Robert and Diane's credit too. They're not a reference or a backup they're a full borrower on the note. That's why co-signing is a serious commitment, not a favor to be asked lightly.
Which Loans Allow Co-Signers
Conventional loans (Fannie Mae and Freddie Mac) allow non-occupant co-borrowers on primary residence purchases, with some restrictions. The co-borrower typically needs to be a family member, and the loan must meet standard qualifying requirements. This is what Marcus used.
FHA loans also allow co-borrowers, including non-occupant family members, which can be helpful for buyers with lower credit scores or smaller down payments. The rules are a bit more flexible than conventional, but the mortgage insurance requirements still apply.
VA loans are different. A co-borrower on a VA loan generally needs to be a spouse or another veteran who meets eligibility requirements, and the loan is subject to VA's occupancy and entitlement rules. Non-VA co-borrowers are more restricted. I'll walk you through which program fits your family situation before you apply.
What Robert and Diane Had to Accept
Before they signed, I sat down with all three of them and made sure Robert and Diane understood the risks. Their names would be on the mortgage. If Marcus defaulted, the lender could come after them. The loan would appear on their credit report, which could affect their ability to borrow for anything else including if they wanted to refinance their own home or finance a car.
They also needed to understand that being a co-borrower meant they'd need to provide full documentation tax returns, asset statements, income verification just like Marcus did. The underwriter would review their finances as thoroughly as the primary borrower's.
Robert and Diane were comfortable with all of it. They trusted Marcus, they had the financial strength to absorb the risk, and they saw helping him buy now as better than watching prices climb while he saved for a larger down payment. Not every family is in that position and that's okay. Co-signing isn't required to buy a home. It's one option among many.
The Exit Plan: Removing the Co-Signer
Co-signers aren't stuck on the loan forever. The most common exit strategy is a refinance: once Marcus's income grows and his credit strengthens, he can refinance the mortgage in his name alone, removing his parents from the loan and the title. This typically takes two to three years of on-time payments and income growth.
Another option is selling the home and paying off the loan, which releases the co-borrowers. Or, if Marcus builds enough equity and income, a loan modification or assumption might be possible though that's less common with conventional loans.
Robert and Diane's plan was a three-year horizon. Marcus committed to refinancing them out by age 28, and they structured their finances so that the co-signed loan wouldn't interfere with their own retirement plans. He closed on his Spokane home in March. His parents were at the closing table not just as co-borrowers, but as the family that made it possible.
If you're considering asking a family member to co-sign, or you're a parent thinking about helping your child buy, let's talk through the numbers and the risks together. I'll show you exactly what it means for everyone's credit, finances, and future borrowing ability. This is not a commitment to lend. Co-borrower eligibility depends on loan program and lender guidelines.
Have questions about your mortgage?
Book a free 15-minute call with Peter no credit pull required.
Related Articles
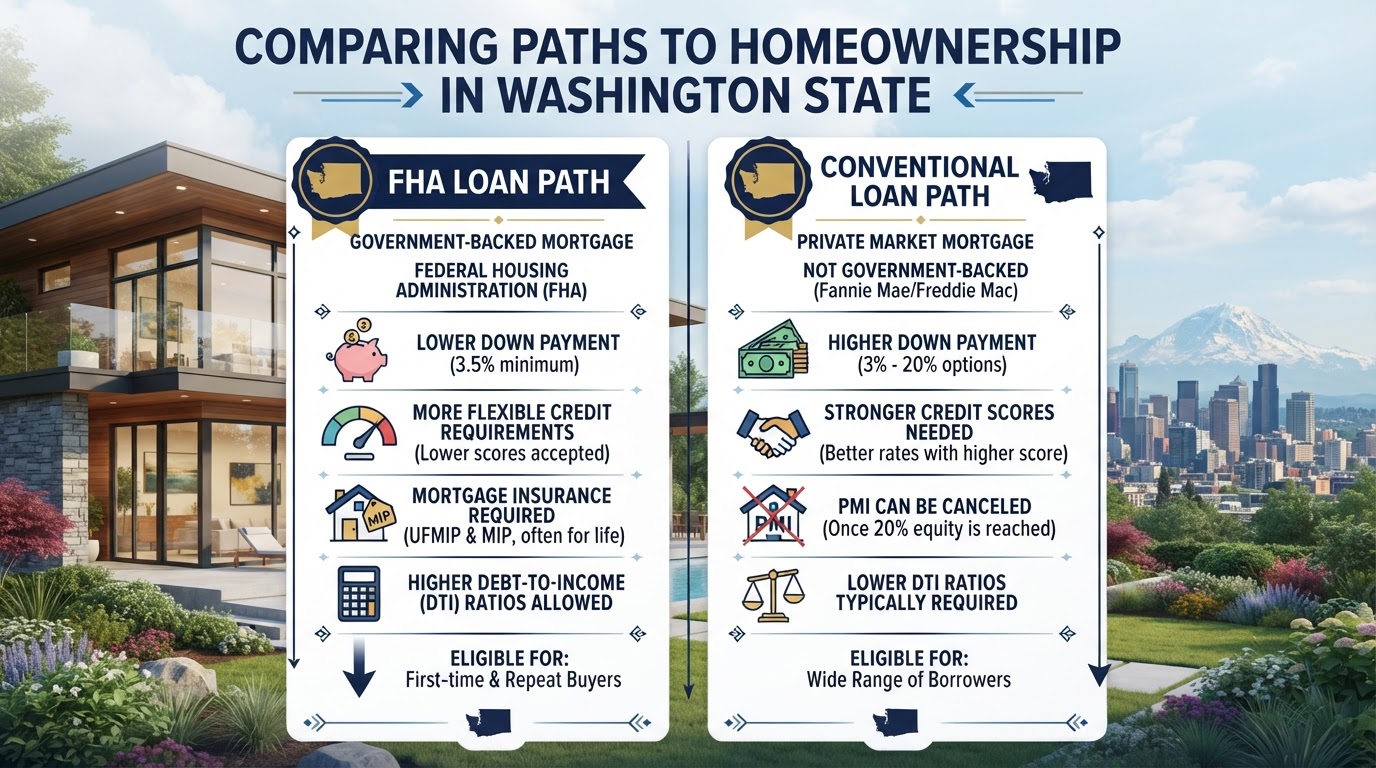
FHA vs Conventional Loans in Washington State: Which Is Right for You?
Comparing down payments, mortgage insurance, credit requirements, and costs to help Washington buyers choose between FHA and conventional financing.
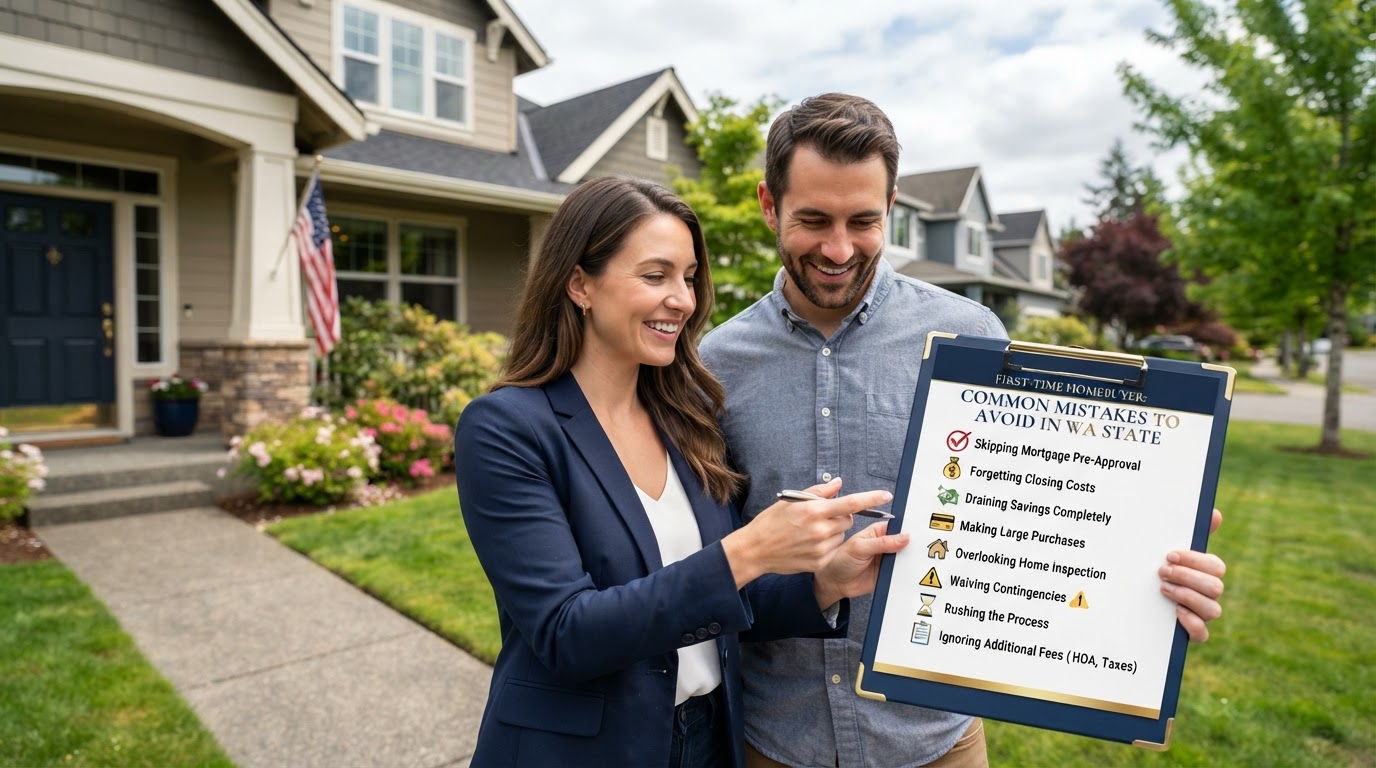
7 First-Time Homebuyer Mistakes to Avoid in Washington State (And How to Dodge Them)
From underestimating closing costs to skipping the pre-approval, here are the most common first-time buyer mistakes in Washington and exactly how to avoid each one.
Condo vs. House in Washington: Which Is the Smarter First Purchase?
HOA fees, appreciation, maintenance, and lifestyle the real pros and cons of buying a condo versus a single-family home for Washington first-time buyers.